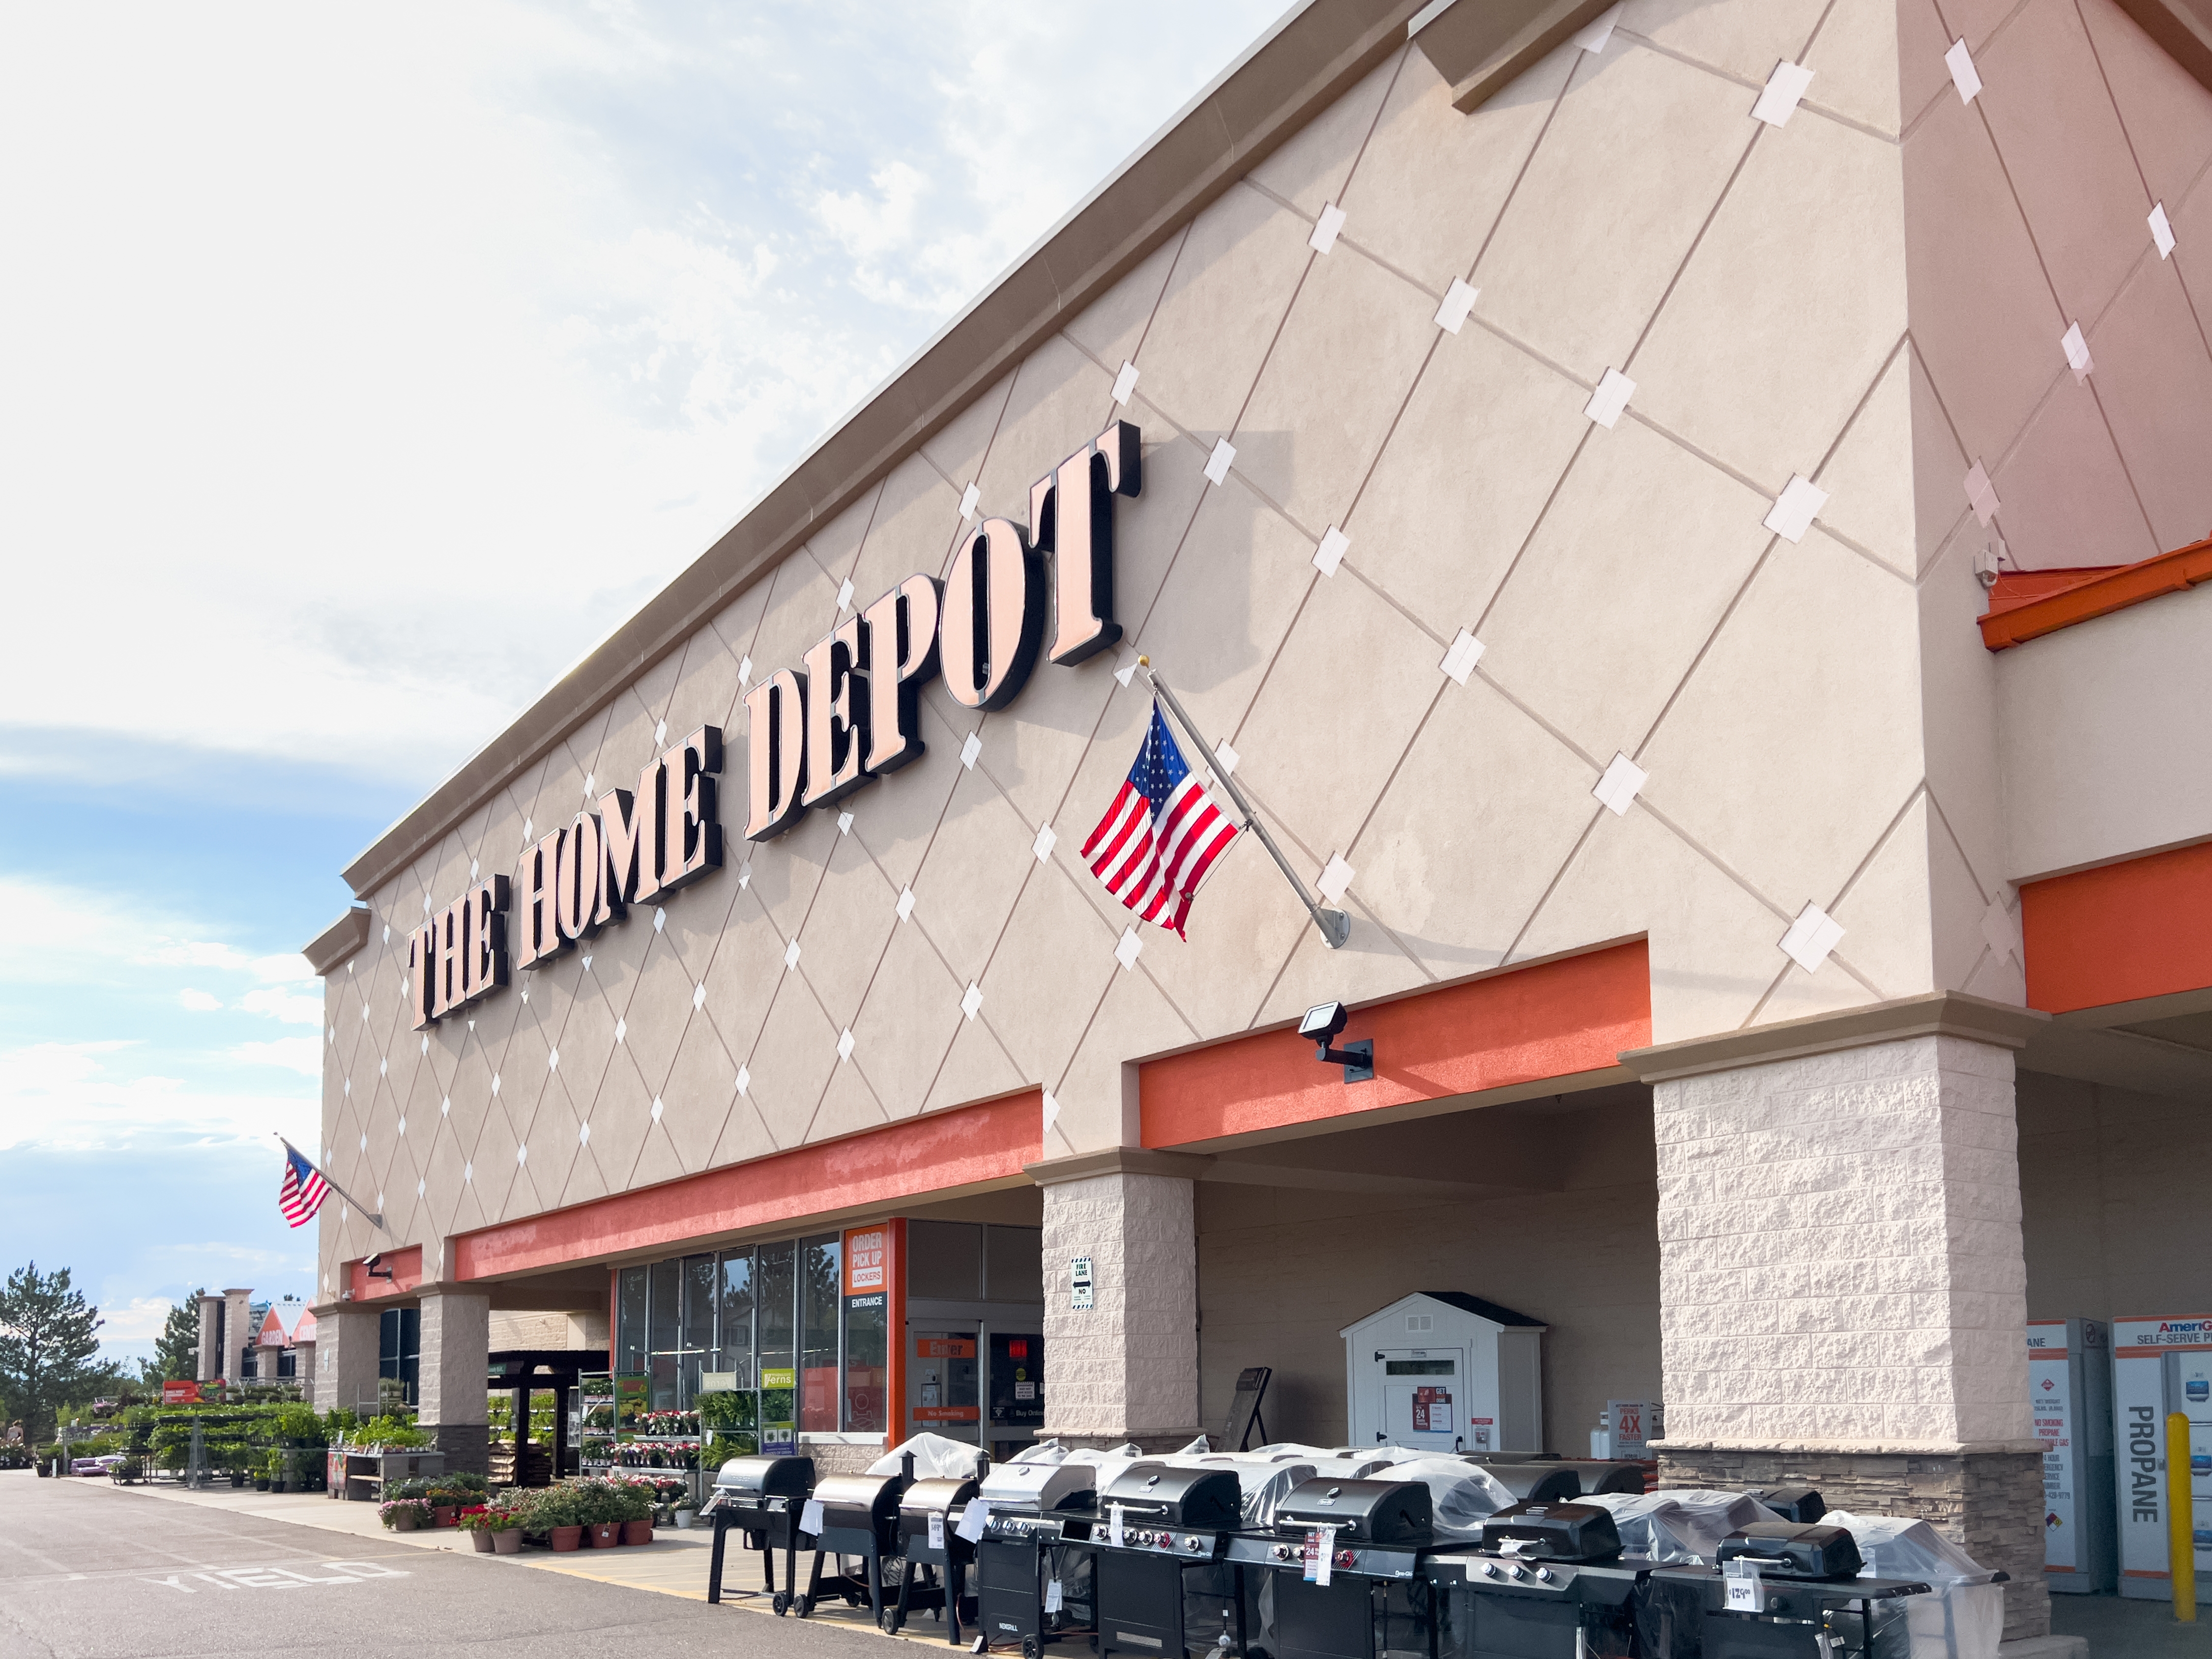
Spring does not just change the weather.
It changes what people do with their houses.
Roofs get patched. Decks get rebuilt. Lawns get upgraded. Kitchens, bathrooms, sheds, fences, paint, grills, mulch, tools, and lumber all move higher on the to-do list once the weather breaks. That is why home-improvement names tend to get a second look this time of year, especially when the stocks have already been knocked down. Harvard’s Joint Center for Housing Studies said spending on improvements and maintenance to owner-occupied homes is still expected to remain elevated through 2026, even if growth slows later in the year.
That is the real setup here.
This is not just about seasonal hope. It is about two dominant operators that still sit in the middle of repair, maintenance, and renovation spending while their stocks trade well below recent highs. Home Depot and Lowe’s do not need a housing boom to work. They just need people to keep fixing, improving, and upgrading the homes they already have. In a market this nervous, that kind of demand still matters.
The Category Leader
Company: Home Depot (SYM: HD)
The dominant big-box home-improvement retailer, with scale across both DIY and professional demand.
Home Depot is still the easiest name in the group to understand.
It is the category leader, and the company still benefits whether spending comes from do-it-yourself customers or pros. In its fourth-quarter and fiscal 2025 results, Home Depot said the board approved a 1.3% increase in the quarterly dividend to $2.33 per share, or $9.32 annualized, payable on March 26, 2026, to shareholders of record on March 12, 2026. With the stock trading around $335.56 on April 8, that works out to an indicated yield of about 2.78%.
The market has not exactly been generous.
Recent coverage noted Home Depot was down about 5% in 2026 and trading below key moving averages before its latest rebound. Barron’s also highlighted the stock as potentially forming a double bottom near the $314 area, with possible upside toward the $375 range if support holds. That is not a guarantee. But it does line up with the broader idea that a lot of bad news around rates and housing has already been priced in.
That is what makes the dip interesting.
Home Depot does not need everything to go right at once. It just needs the usual seasonal lift in project activity, a less hostile rate backdrop, and stable underlying demand. The company itself said underlying demand was relatively stable throughout the year after adjusting for storms. That is not booming demand. It is sturdy demand. In a stock this liquid and this well owned, sturdy can be enough.
The Other Heavy Hitter
Company: Lowe’s (SYM: LOW)
The number-two home-improvement giant, with a strong pro focus, a live dividend, and a stock still well below its highs.
Lowe’s is the cleaner value setup if investors want the same seasonal theme through a different name.
On March 19, 2026, Lowe’s declared a quarterly cash dividend of $1.20 per share, payable on May 6, 2026, to shareholders of record on April 22, 2026. The stock closed at $231.61 on April 7 and had recently traded around $235.20 on April 6, leaving the indicated annual yield a little above 2%.
The recent quarter was not bad.
Lowe’s reported fourth-quarter 2025 diluted EPS of $1.78, compared with $1.99 a year earlier, and highlighted charges tied to the acquisitions of Foundation Building Materials and Artisan Design Group. Those deals matter because Lowe’s keeps leaning harder into the professional customer, where larger ticket sizes and recurring project demand can help offset softer discretionary DIY spending.
The stock is still carrying scar tissue.
Lowe’s remains about 21% below its 52-week high of $293.06 as of April 7, which means the market is still treating the name with caution. But that is also the point. Investors are not being asked to chase perfection here. They are being offered a market leader in a seasonally favorable category, with a live dividend and a business that should benefit if even a modest improvement in housing sentiment shows up as the weather warms.
That is the better way to frame the trade.
This is not really about “war-driven pullback” versus “warm-weather rally.” It is about two dominant retailers whose stocks have already corrected while the calendar is about to turn in their favor. Seasonal demand does not fix everything. But it can help re-open the conversation around quality names that the market got too comfortable ignoring.
Bottom line:
Home Depot is the category leader with the bigger installed base and a yield around 2.8%.
Lowe’s is the cleaner secondary play, with a yield just above 2% and a stronger catch-up profile if sentiment improves.
Different flavors of the same idea.
If the market is finally giving investors a better entry into home improvement right before the busiest project season of the year, it makes sense to pay attention.
Trending Now: The SpaceX IPO makes me FURIOUS
Elon has reportedly filed to take SpaceX Public... in an IPO that's expected to hit a $1.75 trillion valuation.
The biggest in Wall Street history...
And you know who's going to make all the money? The banks brokering the deal. The hedge fund managers. The billionaire insiders. The same "already rich" 1%'ers.
After the IPO, everyone else will be left fighting over scraps.
That's why I'm leveling the playing field.
Found this helpful? Share it with others.
Written by Ian Cooper