Why $1 Billion to $10 Billion Companies Offer the Ideal Balance of Compounding Growth, Balance-Sheet Durability, and Substantial Valuation Discounts
Most portfolios lean on two ends of the market. One end is the mega-cap giants that dominate the major indices. The other is small caps, which carry higher risk and bigger swings. Mid-cap stocks sit in between, and they often get less attention than either.
Understanding how to invest in mid cap stocks starts with knowing how these companies differ from larger and smaller businesses, what drives their performance, and what risks to consider. This guide covers what mid-caps are, how they have performed, what to check before you buy, and the mistakes to avoid. It also shows how Behind the Markets looks for undervalued mid-cap companies.
💡 QUICK ANSWER: WHAT ARE MID-CAP STOCKS?
Mid-cap stocks are publicly traded companies with a market capitalization of roughly $1 billion to $10 billion. They tend to be more established than small caps and have more room to grow than mega-caps.
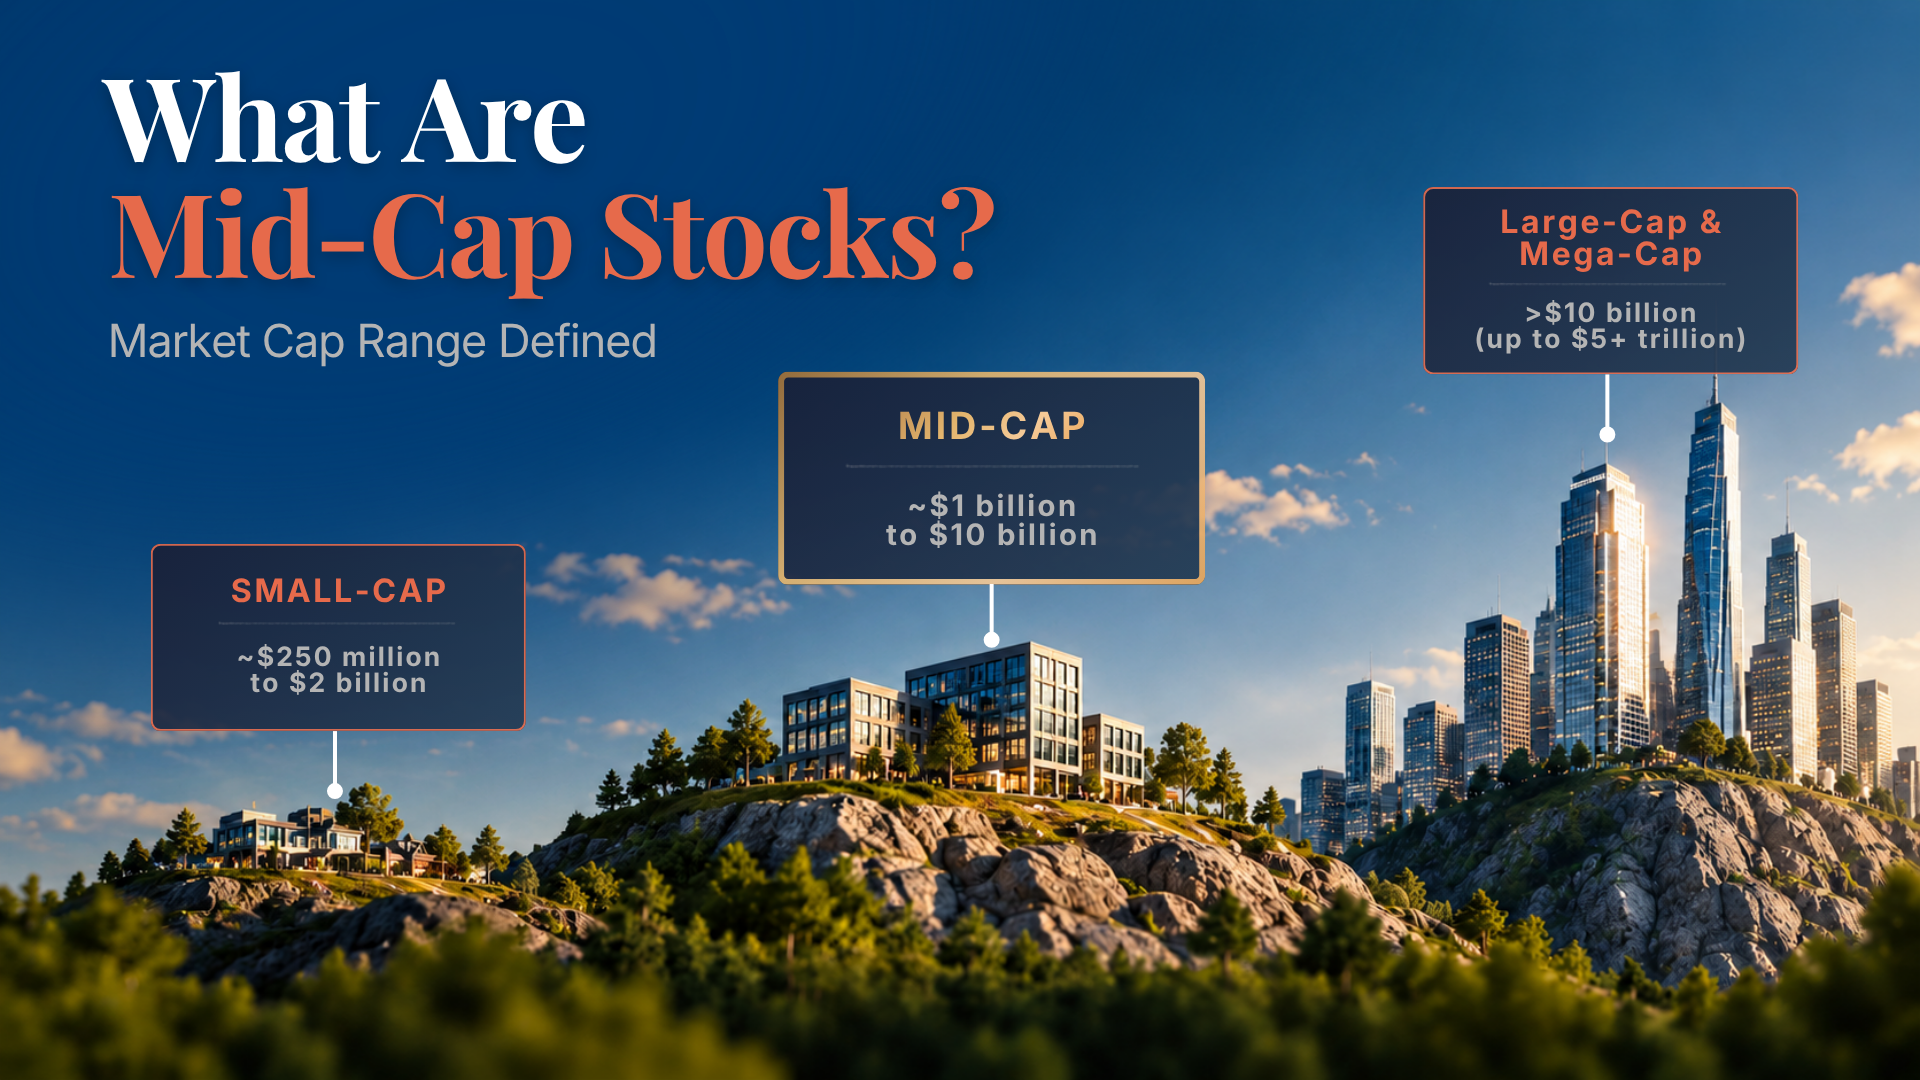
What Are Mid-Cap Stocks? (Market Cap Range Defined)

Market capitalization is the total dollar value of a company's outstanding shares. Investors researching the best mid-cap stocks to buy should understand how index providers and fund companies group stocks into bands, though the exact cutoffs vary:
Small-Cap: Roughly $250 million to $2 billion.
Mid-Cap: Roughly $1 billion to $10 billion. Some managers extend the upper limit to $12 billion.
Large-Cap & Mega-Cap: Above $10 billion, up to market leaders worth more than $5 trillion.
Why $1 Billion to $10 Billion Is a Strong Growth Band
A company does not reach a $1 billion valuation by accident. Many have a proven product, loyal customers, positive gross margins, and access to credit. Yet they are often small enough to keep growing.
Size works the other way for the giants. To double in value, a $3 trillion company must add another $3 trillion. A $3 billion mid-cap faces a much lower bar. A company that lifts its market share from 4% to 12% could see earnings rise significantly over three to five years. That is not guaranteed. It depends on execution, competition, and the economy.
The Mid-Cap Advantage: Growth Potential Between Large Caps and Small Caps
Mid-caps offer a blend that neither end of the market provides. Compared with small caps, they tend to have steadier operations and better access to capital. Roughly 40% of Russell 2000 companies report negative trailing earnings, according to Apollo and Bloomberg data.
Compared with mega-caps, mid-caps have more room to expand and often draw less analyst attention. Microsoft or Nvidia is followed by dozens of analysts. A $3 billion supplier might have only a handful. Large funds also struggle to build meaningful positions in smaller companies, so some mid-caps are overlooked. Less coverage does not guarantee mispricing, though. It can also mean less available information.
Valuations have reflected this insight. SSGA and FactSet data show the S&P MidCap 400 trading at a forward P/E roughly 20% to 26% below the S&P 500 in recent readings. A lower multiple is not a guarantee of value, and discounts can last for years.
Historical Performance and Risk-Adjusted Returns
S&P Dow Jones Indices data shows mid-caps have rewarded long-term investors, with more volatility along the way. The figures below run from December 1994 through March 31, 2025.
Index | Annualized return | Annualized risk | Return per unit of risk |
S&P 500 (large-cap) | 10.7% | 15.2% | 0.70 |
S&P MidCap 400 | 11.5% | 17.9% | 0.64 |
S&P SmallCap 600 | 10.3% | 19.4% | 0.53 |
Source: S&P Dow Jones Indices, S&P MidCap 400 brochure. Return per unit of risk is annualized return divided by annualized risk.
The S&P MidCap 400 earned the highest return, but its return per unit of risk was slightly below the S&P 500's. A 0.8 percentage point annual gap still compounds. Over 30 years, $100,000 grows to about $2.11 million at 10.7% and $2.62 million at 11.5%, before taxes and fees. Mid-caps have not led in every period. In recent years, mega-cap tech has helped the S&P 500 pull ahead, so results depend on the dates measured.
Four Core Criteria for Evaluating Mid-Cap Companies
Not every mid-sized company is a sound investment. Some stall because their business model has reached its limit, and others carry too much debt. These four traits are worth checking. The ranges below are rules of thumb, not universal cutoffs.

1. Sustainable Return on Equity (Often 15% or Higher)
Return on equity (ROE) is net income divided by shareholders' equity. It shows how efficiently management turns shareholder capital into profit. Many investors look for ROE that holds above about 15% across several years, not just one. Check debt alongside it, since leverage can inflate ROE.
2. Low Debt-to-Equity & Solid Free Cash Flow
Debt matters most when rates rise or the economy slows. Companies with floating-rate debt can see interest costs reset higher, and maturing debt may need refinancing at higher rates. Many investors look for net debt-to-EBITDA below about 2.5x. For example, a company with $300 million in debt, $100 million in cash, and $100 million in EBITDA has a ratio of 2.0x.
Consistent positive free cash flow matters just as much. It pays for expansion, buybacks, and dividends without new borrowing. Debt-to-equity is another common measure, and a lower figure generally means less financial risk.
3. Proven Management Track Record
Look at how leaders have allocated capital through a full economic cycle, including acquisitions, buybacks, and debt decisions. Executives who own a meaningful share of the company have interests closer to those of other shareholders. Some studies suggest founder-led companies can outperform, though results vary by period and sample.
SEC Form 4 filings show open-market insider buying. Purchases by CEOs and CFOs can be a positive signal, but they are not a reliable predictor on their own.
4. Durable Economic Moat Against Mainstream Competitors
A durable competitive advantage, often called an economic moat, helps a mid-cap defend its position against larger rivals. Look for specialized niches, such as aerospace fasteners, laboratory testing software, or regional infrastructure. High switching costs or patent-protected processes can give a company pricing power during inflation.
A moat matters most when the market is large enough to keep growing. Strong mid-caps can also attract acquirers, though no deal is ever assured.
Common Pitfalls When Investing in Mid-Caps (And How to Avoid Them)
Knowing the following pitfalls can help you make better investment decisions and avoid costly mistakes:
Value traps. A stock trading at 8x earnings is not automatically a bargain. If revenue has been flat for five years and management borrows to maintain the dividend, the business may be in decline. Look for low valuations paired with revenue growth.
Customer concentration. Check Item 1 of the company's annual 10-K filing. If one customer accounts for more than 15% to 20% of revenue, losing that contract could seriously hurt the business.
Sector concentration. Avoid putting your whole mid-cap allocation in high-multiple technology or biotechnology. Spread holdings across sectors such as industrials, consumer staples, healthcare technology, and financials.
Thin trading. Mid-caps usually trade less than mega-caps, so large institutional trades can move prices sharply without business news. Dollar-cost averaging lets you build a position in several purchases.
Impatience. Mid-caps can re-rate when analysts begin covering them after years of steady execution, though timing is unpredictable. Many investors allow three to five years for a thesis to play out.
How Dylan Jovine and Behind the Markets Screen for Undervalued Mid-Caps
For investors learning how to invest in mid cap stocks, independent research can help simplify the process of reviewing financial statements, assessing debt, and evaluating management teams. Reading 10-K filings, reviewing debt covenants, and following management teams takes time. Some investors use independent research to help with that work.
Behind the Markets, founded by Dylan Jovine, focuses on mid-cap companies with market capitalizations between $1 billion and $10 billion. Dylan has more than three decades of experience in the financial industry. The research looks for companies with high returns on equity, low debt, and a durable competitive advantage. The team often looks at companies after what it believes is a temporary setback has pushed the share price down.
💡 READY TO UNLOCK THE MID-CAP ADVANTAGE?
Are you tired of chasing overvalued mega-cap tech stocks and looking for genuine, overlooked compounders before Wall Street discovers them?
Subscribe to Behind the Markets monthly advisory to receive Dylan Jovine's premier mid-cap stock recommendation every month complete with full financial analysis, price targets, and trade alerts.
👉 Visit Behind the Markets today to claim your risk-free trial and access our latest research dossiers.
Frequently Asked Questions About Mid-Cap Investing
Are mid-cap stocks riskier than large-cap stocks?
Slightly, yes. The risk column above shows higher volatility than the S&P 500, partly because mid-caps trade less. However, many mid-caps have proven business models, access to credit, and positive operating cash flow. Their risk of failure is typically lower than for small-cap or penny stocks.
How much of an investment portfolio should be in mid-cap stocks?
Allocation guidance varies by advisor and investor goals. Some frameworks suggest 15% to 35% of equity exposure. Conservative retirement portfolios may lean toward 15% to 20%, while growth-oriented portfolios may hold 25% to 35%. For context, the S&P MidCap 400 is roughly 5% of the U.S. equity market, so these ranges overweight mid-caps. A financial advisor can help set the right level.
Can mid-cap stocks pay reliable dividends?
Yes. Many mature mid-cap companies generate steady free cash flow and pay dividends, with yields often between 2% and 4.5%. Dividend growth does not always exceed inflation, so check each company's payout history and cash flow.
Should I buy individual mid-cap stocks or a fund?
Funds spread risk across many companies. The SPDR S&P MidCap 400 ETF (MDY) and iShares Core S&P Mid-Cap ETF (IJH) both track the S&P MidCap 400. Individual stocks allow more selectivity but require more research and carry company-specific risk.
Sources: S&P Dow Jones Indices, S&P MidCap 400 brochure (data through March 31, 2025). S&P DJI, The S&P MidCap 400: Outperformance and Potential Applications (2019). S&P DJI Composite 1500 market cap update (July 1, 2025). FactSet and State Street Global Advisors valuation data. Apollo Chief Economist and Future Standard analyses of Russell 2000 earnings (2024 to 2025).
Disclaimer & Regulatory Disclosure: Behind the Markets is an independent financial research publisher, not a registered investment adviser or broker-dealer. The information provided in this guide is for general educational and informational purposes only and does not constitute personalized financial, investment, legal, or tax advice. Past performance, including historical returns of the S&P MidCap 400 or any specific equity, is no guarantee of future results. Investing in securities involves substantial risk of loss. Always consult a licensed financial advisor before making any investment decisions.
Found this helpful? Share it with others.
Written by Research Team