Wall Street Will Sell You "Soft Landing" Monday Morning. The Real World Is Selling Constraints.
A quick note from Behind the Markets
Monday morning is when Wall Street tries to reset the narrative.
This week, they'll try to sell you "soft landing" while the real world screams constraints: energy, logistics, and credit.
Consider the tape you're walking into: Brent crude punched through $100 a barrel Thursday — up 7% in a session, a fifth straight day of gains, its highest since May — the VIX jumped double digits, and the Fed meets Tuesday. That's a lot of potential constraints.
The good news? Retail investors can read the same map the insiders use — you just have to stop watching the index and start watching the bottlenecks. Five of them, below — plus three companies positioned at the choke points instead of beneath them.
1) Warsh's Fed Meets the Real Economy (And Markets Are Underpricing the Tail Risk)
The Federal Reserve meets July 28–29. That's not speculation — it's on the Fed's calendar.
Here's why it matters for independent investors: this isn't about whether they hike or hold. It's about tone and tolerance.
When rates stay high, Wall Street wants you to think the pain is "contained" to a few overlevered zombies.
Reality: the transmission is everywhere — refinancing, small-cap cash burn, regional-bank credit standards, and consumer financing.
This week's macro stack is a stress test — and one correction to the calendar you may have seen elsewhere, because being a day off matters in a week like this:
FOMC decision and Chair Warsh's press conference: Tuesday–Wednesday
Q2 GDP (advance estimate) hits Thursday, July 30, at 8:30 a.m. from the BEA
June Personal Income & Outlays — with the PCE price index the Fed actually targets — follows Friday morning, not Thursday
And remember what the last quarterly PCE reading actually showed: the PCE price index rose at a 4.5% annual rate in the first quarter, with the core index at 4.3%. That's not "solved" inflation. That's the reason the committee removed its easing bias — and with the national average gasoline price now at $4.09 after oil's surge, the July numbers won't rescue the doves.
Translation: one surprise data point + one hawkish sentence can flip the tape. Twice. In the same week.
Bottom line: Don't trade the headline "hold vs hike." Trade the reaction function — and assume liquidity can vanish fast when the narrative breaks. No ticker for this section; it's the lens for everything below.
2) Oil's Weekly Surge Is a Monday Problem (Not a Friday Headline)
Energy is back in the driver's seat.
Here's the verified version, because it's even stronger than the weekend chatter: West Texas Intermediate jumped 6.2% Thursday to settle at $92.19 while Brent climbed 7% to $100.69 — crossing $100 for the first time since May — as traders tracked attacks on Saudi oil tankers and disruption risks near major shipping channels, with Houthi strikes on two Saudi tankers in the Red Sea, President Trump warning of "major military punishment," a 13th consecutive night of U.S. strikes on Iran — and Congress splitting on war powers, with the House voting to direct a withdrawal from hostilities while the Senate rejected its version 49–47.
This is the part Wall Street always gets wrong: they treat oil like a one-day trade.
But energy is a tax — and when it spikes, it bleeds into everything with a lag: freight, chemicals, food inputs, airline pricing, consumer psychology. And it lands right as the market tries to front-run "easing" narratives.
Watch the second-order plays, not just the barrels — the companies that get hired when the world decides it needs more barrels.
Company: SLB (SYM: SLB)
The world's largest oilfield services company — reported Friday morning, beat despite a literal war zone, and the street sees ~30% upside.
SLB (the company formerly known as Schlumberger) is the picks-and-shovels of the entire global oil patch — drilling services, reservoir performance, well construction, and production systems across more than 100 countries. When $100 oil persists, producers eventually drill; when producers drill, they pay SLB.
The timing hook: SLB reported second-quarter earnings Friday morning and beat, with EPS of $0.55 against a $0.52 estimate — and it did so despite genuine wartime friction: Iraq remains under force majeure, pressuring near-term operations. The stock entered the print around $47, below both its 50- and 200-day averages after a roughly 6.6% slide over the prior month, which is exactly why the setup is interesting: the consensus is constructive with an average target near $60 — roughly 28% above the recent price — across 20 covering analysts rating it a Buy. There's even a bonus thread from our AI-power coverage: a strategic alliance with Liberty Energy to deliver modular power infrastructure for AI data centers, and a Digital division that crossed $1 billion in annual recurring revenue, growing 15%.
The honest risks: this remains a cyclical service company hostage to producer capex — analysts flagged Middle East disruptions producing flat sequential results and trimmed EBITDA estimates, and the street cut targets steadily through July even while holding ratings (Barclays to $64, Morgan Stanley to $54, BofA to $56). If the war premium leaves crude, drilling budgets and this stock deflate together. And update the numbers before send: the print landed Friday, so Monday's copy should carry Friday's close and any guidance color from the call. This is a "the beat is in hand, the cycle is the bet" idea.
Bottom line: If oil stays elevated into the Fed week, "disinflation" gets fragile fast — and the market's rate-cut fantasy gets punched in the mouth.
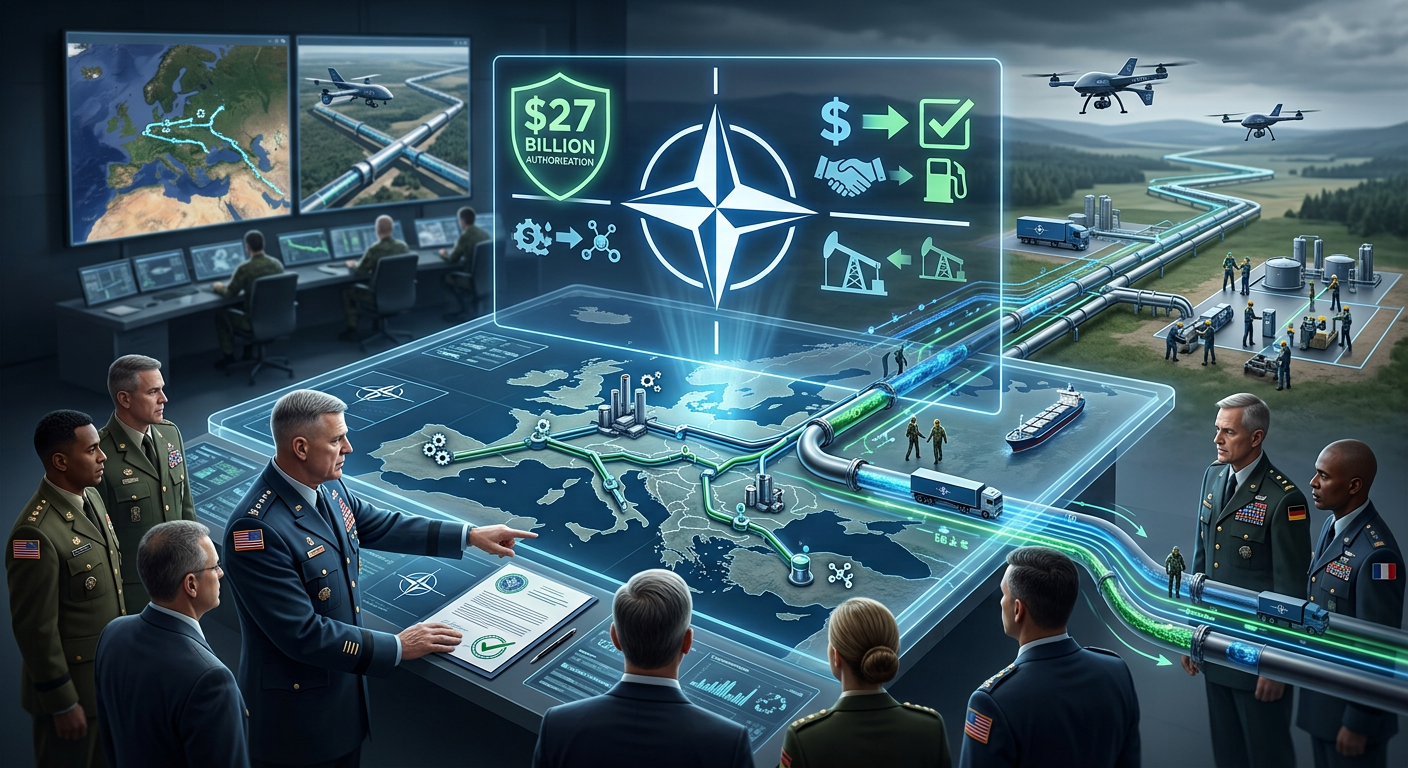
3) NATO Just Dropped a €27B Clue: Modern War Runs on Fuel and Pipes
Most people hear "defense spending" and immediately picture jets and missiles.
That's a rookie mistake.
Here's what actually happened — on Wednesday, while everyone watched earnings: the North Atlantic Council approved NATO's 2027–2031 Common Funding Resource Plan and formalized the Fuel Supply Chain Capability Programme — a €27 billion investment to modernize fuel storage and distribution infrastructure, financing new facilities including pipelines in NATO's eastern and southeastern member states. The scale is historic: it involves upgrading a roughly 10,000-kilometer pipeline network built during the Cold War, spans dozens of projects that could take up to 30 years, and is considered the largest and most expensive program NATO has ever commonly funded — agreed only after Türkiye dropped a last-minute attempt to delay it.
This is the underfollowed investment angle: modern conflict is a logistics and sustainment business. The winners aren't always the prime contractors on TV. They're the quieter names tied to fuel storage and distribution, pipeline and terminal infrastructure, hardened facilities, and the services that keep armies moving.
Most of the direct pipeline work will flow to state operators and private European contractors. But there's one publicly traded company whose entire business is the supply half of that sentence — and it just proved it.
Company: World Kinect (SYM: WKC)
The fuel-logistics specialist that supplies airlines, fleets, and governments — and it just crushed earnings by 72%.
World Kinect is one of the world's great invisible businesses: an energy-management company whose Aviation segment supplies jet fuel and services to commercial airlines, cargo carriers, airports, corporate fleets — and the U.S. and foreign governments and military customers — with Marine and Land segments serving shipping fleets and governments across the Americas, Europe, the Middle East, Africa, and Asia. When fuel gets scarce, expensive, and complicated to move — see every section above — the specialist who can source, price, hedge, and deliver it becomes more valuable, not less.
And Thursday night it showed up in the numbers: World Kinect reported second-quarter adjusted EPS of $1.29 — against a $0.75 consensus — guided the full year to $3.20–$3.40 versus a $2.89 estimate, raised its dividend 15%, and announced additional share repurchases, sending the stock toward its 52-week high near $39.50 from a $36.27 close.
Now the fine print, and it matters: coverage is thin — roughly four analysts — and heading into this print the street was outright skeptical, with Morgan Stanley holding a Sell rating even as it nudged its target to $28 just last Monday. Those pre-earnings targets now sit below the share price, which means either the analysts re-rate or the stock retreats; after a 72% beat and raised guidance, the burden of proof has shifted, but know that you're buying ahead of the street, not with it. This is also a razor-thin-margin distribution business whose GAAP results swing with fuel markets. Size it as the small-cap it is.
Bottom line: Defense is migrating from "platforms" to "persistence." Follow the buildout: fuel, logistics, infrastructure — and the companies already invoicing for it.
4) Crypto's 'Regulatory Week' Is Here — But the Real Trade Is Volatility, Not Victory
Crypto bulls want one thing: a clean rulebook.
This week is being framed as a potential window for Senate action on the CLARITY Act — the market-structure bill drawing brighter lines between SEC and CFTC oversight. Here's the reality check, freshly demonstrated: Bitcoin rallied on reports the Senate was closing in on agreement on key text — then slid roughly 2% below $64,700 as legislative momentum stalled amid renewed partisan friction, even as industry advocates insist the bill is "within reach next week."
A "window" is not a scheduled vote. And a draft is not a deal.
For markets, that means headline-driven spikes, sudden reversals when procedural realities hit, and options pricing that matters more than your opinion on the bill.
So here's the contrarian setup — don't bet on the bill. Own the house where all that indecision gets priced.
Company: Cboe Global Markets (SYM: CBOE)
The exchange that sells volatility itself — beaten down 27% on disruption fears while its volumes hit all-time records.
Cboe runs the world's premier volatility franchise — the VIX complex and four U.S. options exchanges — and its business model is beautifully indifferent to which way markets move. Chop is the product. And the chop is generating records: Cboe reported record trading volumes across its four U.S. options exchanges in June, including a single-day high of 33.4 million contracts — with the VIX spiking 12% on Thursday into exactly the kind of week Section 1 describes.
So why is the stock on sale? Because Wall Street is having an existential panic about exchanges: the shares fell 27.6% in a month at one point on fears about competition from prediction-market platform Polymarket, and TD Cowen slashed its target from $365 to $263, citing "terminal value" concerns as crypto perpetual futures gain attention — even while conceding volumes look favorable. Regular readers know we rejected another exchange from these pages over the same perpetual-futures disruption — but here's the distinction that matters: that company's response was to sue. Cboe's response was to launch — rolling out its own prediction-markets suite, Cboe Predicts, with S&P 500 binary contracts, and partnering with Charles Schwab to distribute them, while RBC calls the perpetual-futures risk "manageable" given Cboe's structural advantages. The stock trades around $255 against a consensus target near $312 — roughly 22% below the street even after the cuts.
The honest risks, stated loudly because they're real: the disruption thesis might be right — if perpetual futures and prediction-market upstarts permanently compress exchange multiples, the old $350 targets never come back, and the wide target dispersion ($258 Underweight at Morgan Stanley to $347 Overweight at Barclays) tells you smart people genuinely disagree. Softer volatility would hit volumes. And the calendar: Cboe reports Q2 before the open on Friday, July 31 — the same morning as the PCE print. This is a contrarian buy of a toll booth during a panic about toll booths. Size accordingly.
Bottom line: Trade the structure (liquidity + volatility + positioning), not the politics. A bill can fail and still produce a monster trading week — and Cboe gets paid either way.
5) The Week-Ahead Checklist (What I'm Watching, Not What CNBC Is Selling)
Here's the simple framework for Monday — no ticker, just the control panel:
Does oil stay above $100? If yes, inflation complacency is vulnerable — and watch gasoline at $4.09 seep into consumer psychology.
Does the Fed sound tolerant Wednesday? If not, risk assets can re-rate lower quickly. The June minutes already removed the easing bias.
Does Thursday's GDP confirm slowdown-without-collapse — and does Friday's PCE stay sticky? Slow growth plus sticky prices is the most dangerous regime for crowded longs.
Does the defense/logistics buildout keep getting formalized? NATO just committed €27 billion for 30 years of fuel infrastructure. "Boring" capex outlasts headlines.
Bonus: SLB's Friday call is your read on whether $100 oil is translating into drilling budgets — and Cboe's Friday print tells you what all this indecision was worth.
Bottom line: This is a week for second-order thinking. The index is the distraction. The constraints are the trade.
Before You Go
Here's the contrarian question to sit with this week:
If inflation is "solved," why does every real-world chokepoint — fuel routes, pipelines, power, credit — keep tightening? Why is Brent above $100, why is NATO spending €27 billion on fuel pipes, and why did the VIX jump 12% into the weekend?
Wall Street sells narratives. Markets trade constraints. Today's three names — the driller's toolmaker, the fuel logistician, and the volatility toll booth — get paid on the constraints.
Found this helpful? Share it with others.
Written by Behind the Markets