Morning Watchlist: Tuesday Edition
A quick note from Behind the Markets
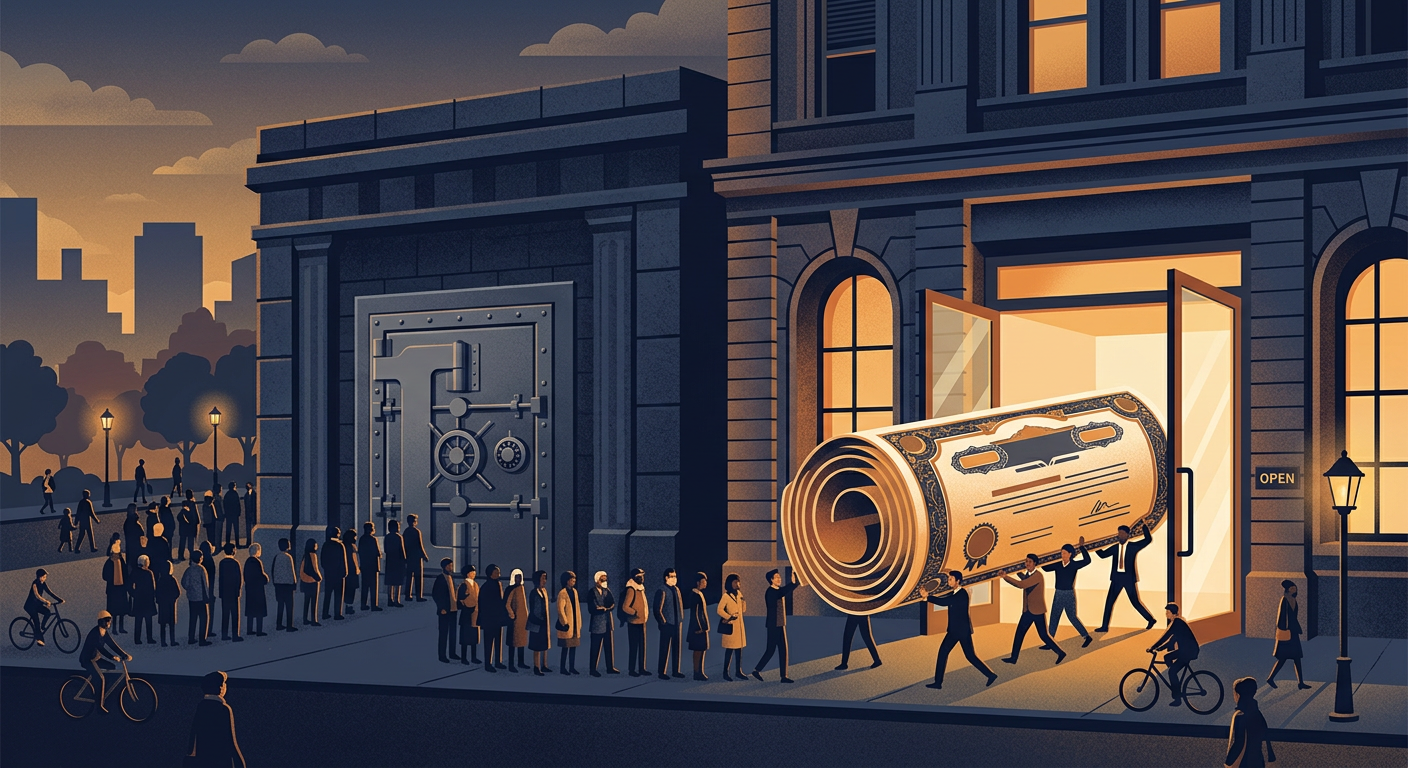
Two lines formed on Wall Street last week.
One was outside the private credit industry: investors asking for their money back and being told — again — that most of them can't have it. The other formed inside a conference room, where bankers began assembling $60 billion of new debt to buy AI chips.
Money pounding on a locked door in one building; money signing a long lease next door. Both lines run through the same bond market — which takes delivery this week, as the Treasury auctions $119 billion of notes and bonds with the 10-year yield near 5.28%.
Three stories this morning. Three pairings. Let's get into it.
1) The Line Outside the Locked Door
On Friday, Blue Owl Capital capped withdrawals from two of its private credit funds — again. Investors in the two vehicles asked to pull 39% and 17% of their money this quarter. The funds will honor 5%. Apollo and Ares capped funds the same way earlier this year, Partners Group just split its flagship private-equity fund, and a string of borrower failures has kept the $1.8 trillion sector's nerves raw. Blue Owl closed Friday at $9.08 — roughly a third of its early-2025 peak — yielding 10%, a payout the market plainly doesn't believe.
For a decade, private markets sold illiquidity as a feature: you can't panic-sell what you can't sell. That slogan is now being tested. A gate stops a redemption. It doesn't stop the need for cash. An institution that can't get out through the front door sells its fund stake out the side — on the secondary market, at a discount, to whoever has ready money.
Somebody runs that consignment shop.
The pairing: StepStone Group (STEP) — Buy
StepStone is a $5.5 billion private-markets firm that invests on behalf of pensions and sovereign funds — and runs one of the industry's larger secondaries platforms, the desks that buy fund stakes from sellers who need out. It just closed a $1.7 billion infrastructure secondaries fund. Think of an estate sale on a street where every house is locked: the one buyer walking the sidewalk with cash doesn't just get a deal. He sets the price.
The market sold StepStone with the panic. At Friday's close of $45.27, the stock sits 42% below its 52-week high while the business grew: June-quarter management fees rose 27%, fee-related earnings rose 30% at a 39% margin, and assets under management reached $245 billion, up 23%. The price of that: about 15 times next year's expected earnings. The S&P 500: 21. The dividend — including a supplemental payout — runs about 4%, and nine covering analysts say Buy, average target $69.56, more than 50% above the price. One accounting note, the same caveat we gave at Jackson and Global Payments: the GAAP line shows a loss driven by equity-compensation charges — fee-related earnings are the run rate.
The honest risks. StepStone sells funds to wealthy individuals too, in the same evergreen wrappers now making headlines — if the gating panic reaches its own vehicles, the consignment shop becomes the seller. Performance fees fell 28% last quarter. And a genuine freeze in private-markets fundraising starves the fee engine.
2) The AI Boom Took Out a Mortgage
Here's the other line. Bloomberg reported Friday that Broadcom has started assembling $60 billion of debt — a $42 billion senior-secured slice syndicated through banks, plus an $18 billion junior slice led by Blackstone — to finance custom AI chips for Anthropic, which is expected to become Broadcom's largest compute customer next year. The same week, Nvidia touched a record high near $238 — a market value around $5.5 trillion — days after authorizing a $150 billion buyback, the largest in stock market history.
See the turn? For three years, the AI build-out was paid for out of cash flow. Now the financing has moved to the bond market: Broadcom's $60 billion, Oracle's borrowing, a widening web of leases and special vehicles, all priced against a 5.28% ten-year. We've owned the bulldozers, the switchgear, and the optical fiber of this build-out. Today we're interested in the paperwork. Because every IOU in a land rush, whoever wins the land, crosses one desk on its way to a buyer.
It needs a grade.
The pairing: Moody's (MCO) — Buy
Moody's is the notary of the debt boom — one half of the ratings duopoly that stamps nearly every bond that wants institutional money. It rated a record $6.6 trillion of debt in 2025. Its private-credit ratings revenue grew nearly 60% last year — gates and all, opaque credit is exactly what investors now demand an independent grade on, and Moody's just launched a credit-risk model built for that market. Management projects debt-funded M&A issuance up 40–45%.
And the stock is having a rare off year: down 13% in 2026 to $441, against a 52-week range of $379 to $547, at about 28 times earnings — a premium to the S&P's 21, but below its own usual altitude in the 30s. Twenty-four analysts rate it a Buy, average target near $562, about 27% above the price. A large cap, but the pairing is the strength — the same exception we made for Goldman.
The honest risks: 28 times is no bargain cushion — quality at a fair price, not a washout. A rate shock that slams the issuance window shuts the toll booth, the same risk we carry at Goldman and Nasdaq. And if the private-credit cleanup turns into a hunt for someone to blame, the raters have sat in that witness chair before. The kill: issuance actually contracting while the multiple stays premium.
3) A Hundred Million Barrels of Relief
Quietly, on Friday, the G7 agreed to release up to 100 million barrels of diesel and crude from strategic reserves — substantial diesel within 20 days, the rest over four months — after the Gulf war and Russian export bans drove diesel to a record $6.52 a gallon in late September. Analysts project 25 to 50 cents a gallon of relief. Macron's words: "This common decision and this unity should bring down prices." Oil fell about 2% Friday, to $91.11, even as OPEC+ held its November quotas.
This is the "cheerful loss" we named at Magnolia and Darling, arriving by committee instead of by peace treaty — Darling's record diesel crack spreads are the release's direct target, now the formal watch item there. GATX's record-diesel tailwind eases too, though the rail thesis was never a four-month trade. ONEOK gets paid per barrel moved either way; that's why we own it.
Remember J.B. Hunt's September warning: millions in extra fuel costs, because surcharges lag the pump by a week. The market forgets that the lag works in both directions. A fuel surcharge is a speedometer that reads last week's speed. On the way up, it bled the truckers. On the way down, they bill last week's diesel while buying this week's.
The pairing: Knight-Swift Transportation (KNX) — Watch
Knight-Swift runs the largest truckload fleet in North America — a $10.8 billion company whose earnings the freight recession has flattened to almost nothing: trailing earnings per share of 26 cents, down 74%. That's why the trailing multiple reads a meaningless 250 while the forward one reads about 20. Twenty-one analysts rate it a Buy, average target $88.45, well above Friday's $66.35.
So why Watch and not Buy? Because at 20 times next year's hoped-for earnings, the recovery is already on the ticket — and relief from a strategic reserve is borrowed, not earned. Reserves get drained once and refilled later. We'd rather see the fuel tailwind reach the income statement: earnings land October 21st, and that's the entrance — cheaper diesel showing up in margins with freight rates holding, or a markdown that pays us for the cycle risk. The kill: a 29,000-jobs economy simply ships fewer boxes. Falling demand outruns any fuel rebate.
Before You Go
Busy day today. Prime Big Deal Days opens this morning — the first live test of our GXO call — and the Paramount–Warner merger is set to close, bolting the 45-day theatrical window into place for Cinemark and the express lane IMAX is still priced too dearly to merge into. Wednesday at 2 PM, the Fed's September minutes land in a market pricing 84% odds of an October hold — though the $39 billion 10-year auction the same day may be the louder referendum, and Tradeweb gets paid on the arguing either way. Thursday, PepsiCo confesses with Ingredion one aisle behind. Friday, Delta reports, with our AAR entrance and Copa's unhedged fuel bill — just lightened by the G7 — both listening.
That's the watchlist: the consignment shop outside private credit's locked doors, the notary stamping the AI boom's new mortgage, and a trucking fleet we'll board only when the fuel rebate hits the ledger. One theme, as always: the best opportunities stand one step behind the headline.
Found this helpful? Share it with others.
Written by Behind the Markets