The Nuclear Trade Just Got Real. Here's How to Own the Buildout — Not the Hype.
A quick note from Behind the Markets
Happy Independence Day!
While everyone is watching fireworks, we want to talk about a number that came out of McKinsey's Q2 consumer survey — because it quietly reframes a lot of what Wall Street is saying about "the resilient consumer."
The share of US consumers who feel optimistic about the economy just hit its lowest level in two years. Optimism dropped five percentage points in a single quarter. And the pullback in discretionary spending intentions is broadening — even high-income consumers say they may cut back on "nice to haves."
This isn't a crisis. But it is a regime change. And regime changes reward the investors who see them early.
1) The Consumer Bifurcation Just Got McKinsey Data — And It's More Extreme Than You Think
McKinsey's Q2 2026 ConsumerWise survey is worth sitting with.
Optimism about the economy fell to 35% of consumers — the lowest reading in two years, down five percentage points in a single quarter, the biggest quarterly drop in the series. Pessimism rose by four points. The most cited concern was cost of living. And notably, while lower-income consumers were already the most downbeat, it was high- and middle-income consumers who reported the largest declines in optimism this quarter.
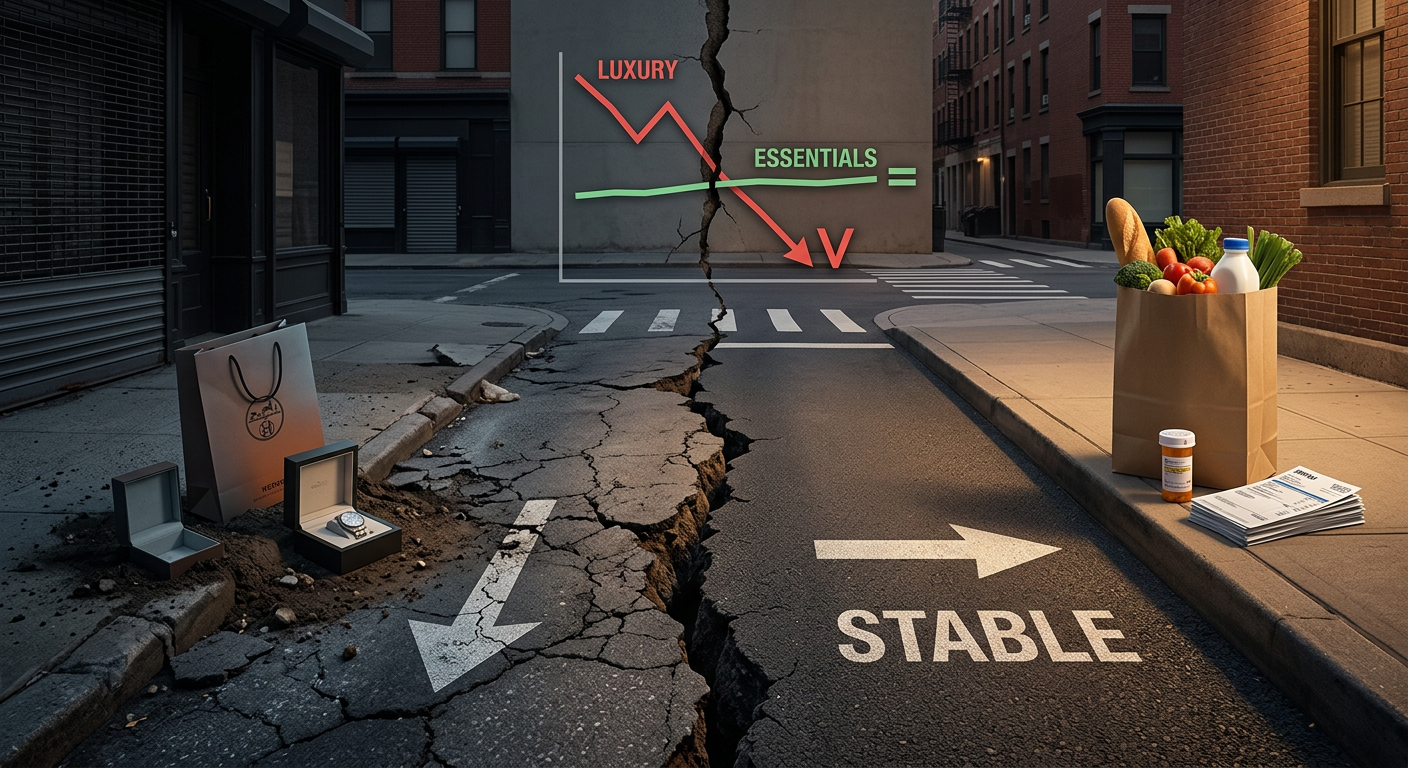
What does that look like in spending behavior? Intent to spend in discretionary categories declined broadly. Big-ticket and self-expression retail — accessories, jewelry, home décor, furniture, sports and outdoor equipment — saw the steepest pullback. In many of these categories, 40 to 50% of consumers say they plan to spend less over the next three months, while the share planning to spend more sits in the low-to-mid teens.
But here's the split: essential categories held up (net intent for fresh produce actually rose), and domestic travel and experiences — restaurants, hotel stays, short-term rentals — remained resilient, driven primarily by higher-income households. More than three-quarters of consumers now report some form of trade-down behavior.
The investment implication is specific: the company serving the high-income experiential consumer is in a completely different business than the one serving the mass-market discretionary consumer. So own the former.
Company: Marriott International (SYM: MAR)
The world's largest hotel company, with a luxury-skewed, asset-light, fee-based model aimed squarely at the higher-income traveler
Marriott is a direct play on the one discretionary category the data says is holding up: higher-income travel and experiences. Its portfolio skews premium — Ritz-Carlton, St. Regis, W, Luxury Collection — exactly the brands whose guests are least exposed to the cost-of-living squeeze. And the model is asset-light: Marriott mostly collects franchise and management fees rather than owning buildings, so it earns high-margin, recurring revenue as room rates rise. Q1 2026 beat expectations (EPS $2.72), with global RevPAR up 4.2%, gross fees up 12%, and adjusted EBITDA up 15% to $1.4 billion. It just raised its dividend 9%.
MAR trades around $383, near the upper end of its 52-week range ($254–$411). The honest caveats matter here: it's fully priced at roughly 37x earnings, so there's little room for error; the Middle East is a real drag (RevPAR there was down sharply and is guided to fall ~50% in Q2); travel is discretionary and cyclical, so if the higher-income consumer finally cracks, Marriott feels it; and insiders have been selling. This is "own the premium end of a bifurcated consumer," not a bargain. If you'd rather emphasize pure pricing power, Hilton (HLT, even more asset-light) and Ferrari (RACE, ultra-luxury with a multi-year order book) are two alternatives on the same theme.
Bottom line: "The consumer is fine" is true — for roughly the top third of households. For everyone else, the pressure is intensifying. Owning "consumer stocks" as a monolith right now is a mistake.
2) The Grocery Trade Is Not Boring — It's a Margin War
Here's a granular data point worth isolating: grocery and essential-food spending intent firmed up this quarter. That sounds like good news for grocery retailers. It is not — at least not straightforwardly.
When consumers are forced to spend more on groceries because food prices are elevated, that doesn't mean they're buying more volume. It means they're paying more for the same basket. And when they're doing that, they're also trading down to store brands, comparing unit prices more carefully, cutting impulse buys, and shifting from conventional grocers to warehouse clubs and discount formats.
The winners in elevated-necessity grocery spending aren't the premium grocers. They're the formats that offer volume and value. The losers are conventional supermarkets with thin margins and limited private-label penetration. The cleanest way to own the winning format is the one that turns value into a membership moat.
Company: Costco Wholesale (SYM: COST)
Membership warehouse club; the flagship "volume and value" format and a prime trade-down beneficiary
Costco is the textbook winner of a trade-down grocery market. Its whole model — bulk sizes, razor-thin markups, dominant Kirkland private label — is built to deliver the lowest unit cost, which is precisely what a squeezed but necessity-driven shopper hunts for. And the genius is the membership fee: roughly $1.4 billion a quarter in high-margin, recurring dues that renew above 90% and let Costco keep prices low to drive traffic. The formula is working — May comparable sales rose 12.5%, and it just hiked its dividend 11%.
COST trades around $925, about 15% below its 52-week high near $1,097 (note the high per-share price — fractional shares help for smaller accounts). The honest caveats: even after the pullback it's expensive at roughly 50x earnings, so it prices in years of flawless execution and would fall hard on any stumble; its dividend yield is tiny (~0.5%); and much of its profit rides on membership renewals rather than merchandise margin. This is a quality compounder at a premium, not a value play. For cheaper exposure to the same format, BJ's Wholesale (BJ) trades at a fraction of Costco's multiple, and dollar-format food retailers capture the lowest-income end.
Bottom line: The consumer data this quarter is a roadmap, not a headline. Grocery "strength" this summer is a private-label and warehouse-format story — not a broad grocery-retailer tailwind.
3) The Trade-Down Winner: Where the Squeezed Discretionary Dollar Actually Goes
There's a third move hiding in this data, and it's the most under-appreciated of all.
The bifurcation story tells you to own the high end (Section 1) and avoid the mass-market discretionary middle. But the mass-market consumer doesn't stop buying clothes, shoes, and home goods entirely — they just refuse to pay full price for them. And here's the part that makes this a rare "own both sides of the K" trade: when higher-income households start trimming their own "nice to haves," they trade down too. Both ends of the income spectrum funnel into the same place — the off-price channel, which sells brand-name merchandise at a steep discount.
That's exactly the structural trade-down McKinsey is describing: more than three-quarters of consumers optimizing purchases, hunting value, and buying the same brands cheaper. The off-price retailer is the discretionary-goods equivalent of the warehouse club — and it feeds on this environment.
Company: TJX Companies (SYM: TJX)
Operator of T.J. Maxx, Marshalls, and HomeGoods; the dominant off-price retailer and a two-sided trade-down winner
TJX is built for precisely this moment. It buys brand-name apparel, footwear, and home goods opportunistically — often more cheaply when the full-price retailers it competes with are stuck with excess inventory — and sells them at a discount that pulls in bargain-hunters from every income tier. That treasure-hunt model drives high traffic and rapid inventory turnover, and it works in both good times and bad: value-seeking is the whole proposition. Recent results back it up — comparable sales grew 6%, the company returned $1.1 billion to shareholders, and in consumer surveys 71% cited it as a go-to value destination. It runs more than 5,000 stores across nine countries and does roughly $60 billion in annual sales.
TJX trades around $155, just off its all-time high near $170 (52-week low $120). The honest caveats: it's no longer cheap (~29x earnings), a genuine consumer collapse would eventually hit even off-price, roughly a quarter of sales come from Canada, Europe, and Australia (so it isn't purely domestic), and it depends on a steady flow of discounted inventory that a lean-inventory retail environment could pinch. This is a "the trade-down is structural, own the beneficiary" idea, not a bargain. For alternatives on the same theme, Ross Stores (ROST) is the more purely domestic off-price play, and Burlington (BURL) is the higher-growth, higher-volatility one.
Bottom line: The bifurcation isn't just "own luxury, avoid the middle." The squeezed discretionary dollar doesn't vanish — it migrates to off-price. Own where the money actually goes.
Before You Go
The Independence Day question worth sitting with: is your portfolio positioned for the consumer you think exists — or the consumer the data is actually describing?
The gap between those two things is where a lot of second-half earnings surprises will be born.
Found this helpful? Share it with others.
Written by Behind the Markets