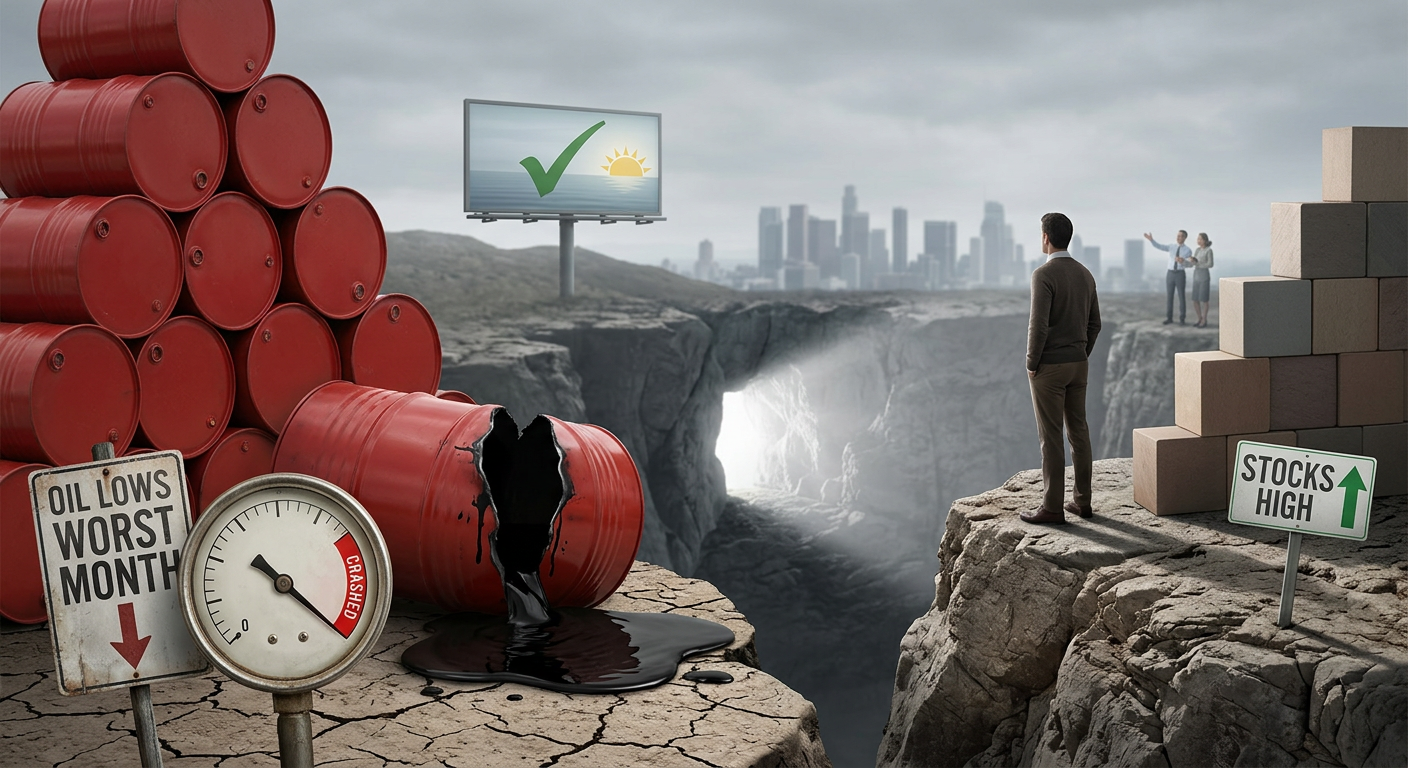
Oil Just Had Its Worst Month Since COVID. Stocks Are at Record Highs. Iran Fired Missiles Thursday. And the Market Says "All Clear."
A quick note from Behind the Markets
Happy Monday.
Wall Street is walking into this week with its chest out. Stocks are at record highs, oil just took a hard hit, and the crowd is already pricing a "back to normal" summer.
That's usually when the market hands out the bill.
1) Oil's Friday Drop Is a Geopolitics Headline — but the Real Trade Is What Happens After the Headline Fades
Friday's market mover wasn't an earnings report. It was a draft deal.
Brent crude closed around $92.50 after dropping about 1.1% on the day. WTI fell to roughly $87.40. For the week, Brent plunged 10.5% and WTI dropped 9.2% — the steepest weekly declines since early April. For May, Brent cratered nearly 19% — its worst month since the COVID pandemic.
Oil is now down roughly 20% from its 2026 peak above $126. The narrative: peace is coming.
The reality underneath is messier. The U.S. and Iran have drafted a 60-day memorandum of understanding to extend the ceasefire and hold a new round of nuclear talks. But Trump hasn't signed it. Iran hasn't publicly confirmed it. And on the same day the deal was reported, Iran fired ballistic missiles at Kuwait and sent attack drones toward the Strait.
UBS says there is "little evidence" of any short-term improvement in vessel traffic or energy flows. Iran crude loadings for May collapsed to below 0.3 million barrels per day — down from 1.5M bpd in April and 1.7M bpd in March. ING warned the market is "more exposed now than before the conflict, due to considerable inventory drawdowns over the past three months." And The National reports 42 ships remain stranded in the strait.
Remember: Brent was $70 per barrel in late February, before the war started. It's now at $92. That's still 32% above pre-war levels. A 20% drop from a panic high is not "the war premium is gone." It's "the market is pricing hope, not resolution."
One company that thrives on oil volatility regardless of direction:
Company: Enterprise Products Partners (SYM: EPD)
The largest U.S. midstream company — 50,000+ miles of pipeline, ~5.8% yield, 26 consecutive years of distribution increases. Fee-based contracts that collect the same toll whether oil is at $87 or $127.
When oil drops 19% in a month and the ceasefire narrative keeps whipsawing prices, the companies that transport oil don't feel the price decline. They feel the volume. And with U.S. LNG exports expanding 50%, the Gulf Coast pipeline buildout (18–20 Bcf/d of new capacity), and AI data centers driving gas demand for power generation, the structural volume story is intact. EPD is the toll road that doesn't need a specific oil price — or a specific geopolitical outcome — to pay you.
Bottom line: Friday's oil drop bought the market a "relief rally" story. The smarter move is tracking the second-order effects: inflation psychology, credit, and who loses funding when the narrative flips back.
2) Week-Ahead: The Market Says "Jobs Report." I Say "Late-Cycle Stress Test."
Next week's marquee event is the U.S. jobs report on Friday, June 5. IG's preview pegs consensus at roughly 93,000 jobs added with unemployment around 4.3%.
But don't trade it like a bingo card.
The S&P 500 is at 7,563. The Dow just cleared 50,669. The Nasdaq sits at 26,917. These are all-time highs — achieved in a world where CPI is at 3.8%, consumer sentiment is at a 74-year low (44.8), inflation expectations are at 4.8%, the 30-year Treasury recently touched 5.14%, and real wages are negative.
Reuters framed it cleanly: U.S. stocks are "soaring," and the jobs report is the next checkpoint as investors weigh inflation, potential rate hikes, and bond yields as risks.
If jobs come in strong, yields push higher and the "everything is fine" equity rally starts to look like a leverage trade. If jobs come in weak, you don't automatically get a Fed pivot — you might get a "growth scare" with earnings risk, especially for the 40–46% of Russell 2000 companies that can't cover interest with operating profits.
Either way, this isn't a week to be lazy.
One ETF built for a world where the jobs report creates volatility regardless of direction:
ETF: Invesco S&P 500 Quality ETF (SYM: SPHQ)
The highest-quality S&P 500 balance sheets — the companies that survive whether the report triggers a yield spike or a growth scare.
SPHQ doesn't need a specific payroll number. Strong jobs? Quality companies have the earnings to justify premium valuations. Weak jobs? Quality companies have the balance sheets to ride through a downturn. In a market at record highs with consumer sentiment at record lows, the quality filter isn't a style preference — it's insurance.
Bottom line: The jobs report is a stress test for positioning. Trade the market you have: record highs, shaky geopolitics, and rates that refuse to die.
3) AI Is Sending the Indexes to Records — but the Next Leg Is About the Unsexy Bottlenecks
Reuters pointed out that AI is sending stocks to record highs. That's the headline. The setup underneath is what matters.
The S&P 500's rally is being driven by a handful of mega-cap AI winners. On a single recent trading day, the market posted 235 new 12-month lows against 120 new highs — while the index was at an all-time record. The equal-weight S&P 500 fell 1.29% the same week the cap-weighted index gained 0.17%. Only 5.6% of components made a new 52-week high.
When everyone crowds into the same AI winners, two things happen: valuations get fragile, and the market stops pricing the industrial constraints.
Half of U.S. data centers planned for 2026 are delayed or canceled — not for lack of money, but because transformer lead times stretch 3–5 years. GPU lead times run 36–52 weeks. All 2026 HBM memory capacity is preallocated at 60–70% gross margins. The $1.4 trillion utility buildout is just getting started. And residential ratepayers in 30+ states are pushing back against footing the bill.
The AI trade is a supply chain story. Not just chips. Not just cloud. It's power delivery, cooling, networking gear, and the manufacturers that can actually ship real hardware on time.
One company shipping the physical infrastructure the AI buildout can't deploy without:
Company: Eaton Corporation (SYM: ETN)
The global power management leader — switchgear, transformers, circuit breakers, and power distribution for every data center and grid upgrade. Record backlog. Mid-teens revenue growth. The physical chokepoint.
When 7 GW of data center capacity is stalled because of electrical equipment shortages and the $635–$700 billion hyperscaler capex machine needs power hardware to deploy, Eaton is the company that manufactures it. Wall Street doesn't like these names because they're boring. That's exactly why retail investors should own them.
Bottom line: When the megacap AI trade gets crowded, the next upside rotates to the bottlenecks. Follow the constraints, not the influencers.
4) The Quiet Small-Cap Opportunity: Disclosure Relief Is Coming — and Wall Street Will Pretend It's "No Big Deal"
This one is wonky. That's why it matters.
Buried in the regulatory pipeline: a proposal to simplify how public companies are categorized (large accelerated filer vs. non-accelerated) and extend scaled accommodations to a broader universe of smaller issuers.
For small caps and micro caps, compliance cost isn't "overhead." It's oxygen. Audit fees, SEC reporting, Sarbanes-Oxley compliance, and legal costs can eat 5–10% of revenue for a company with $50–$100 million in sales — versus less than 0.5% for a mega-cap. When reporting burdens ease at the margin, more companies stay public (or go public), investor relations gets cleaner, and there's less forced dilution to pay the accountants and lawyers.
This intersects with the broader small-cap setup: quality small-caps are trading at their lowest valuations relative to the S&P 500 in over two decades. The Russell 2000 is at 19.5x trailing earnings versus 30x for the S&P. The Butterfield $1.8 billion deal just proved CEOs are underwriting at today's rates. Biotech M&A hit $84 billion in Q1. If disclosure relief lowers the cost of being small and public, and deal flow is reopening — the "too small to care" bucket is where valuations get reset.
One ETF that captures quality small caps positioned for the regulatory and M&A tailwinds:
ETF: SPDR S&P Biotech ETF (SYM: XBI)
Equal-weighted biotech exposure across dozens of small and mid-cap names — the acquisition targets benefiting from Big Pharma's $1 trillion cash pile, the patent cliff, and any regulatory relief that keeps small biotechs public long enough to get bought.
XBI's equal-weight structure means every M&A premium hits the portfolio proportionally. With $300 billion+ in pharma revenue at risk from patent expiries, the buyers are structural. Stifel projects $250 billion in biopharma M&A for 2026. Premiums run 40–60%. If disclosure relief keeps more biotechs public and financially viable long enough to reach late-stage catalysts, XBI's opportunity set expands.
Bottom line: If small issuers get breathing room and deal flow picks up, that's bullish for the right small caps — the ones building real businesses, not financial-engineering stories.
Before You Go
Here's the question at Monday's open:
If peace headlines can drop oil 19% in a month… and stocks are still at record highs… what happens when the next shock goes the other way?
Found this helpful? Share it with others.
Written by Behind the Markets