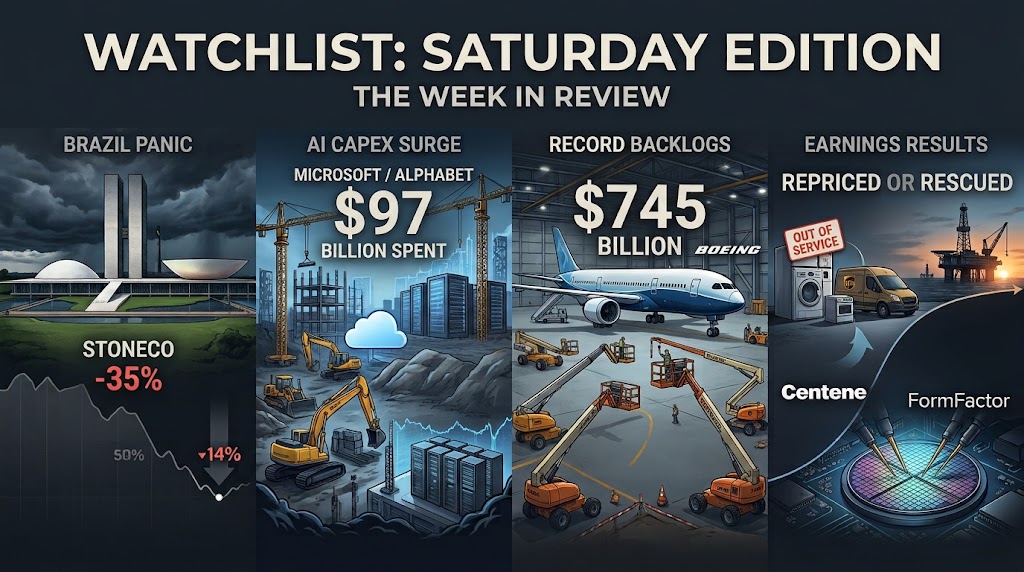
Morning Watchlist: Saturday Edition
The Week in Review A quick note from Behind the Markets
It's Saturday morning — Halloween — and the market spent the week pulling masks off everything it had been afraid of.
Under the Fed mask: a hold, 3.75%–4.00%, on a 10–2 vote, with two members pushing for a hike and Chair Warsh calling the moment "information rich." Under the economy mask: third-quarter GDP grew 3.4% against the 3.2% expected, core PCE ran 3.1%, and jobless claims printed 194,000. Under the AI mask: Microsoft and Alphabet poured nearly $97 billion into data centers in thirteen weeks and promised more. The scary part wasn't what was under the masks. It was what the market did next — Alphabet lost a tenth of its value Thursday over a quarter that included a $561 billion cloud backlog.
And then there was Brazil, where the mask came off a whole country's stock market on Monday morning.
One press note, as always: we go to press Thursday midday, so Friday's session belongs to you, not to us — it leads your Monday checklist below. Twenty-two calls this week, the fullest card we've carried. Four stops on the tour.
Let's get into it.
1) The Panic We Pre-Ordered
On Sunday, Brazil re-elected Lula. The polls missed again, and on Monday the Ibovespa fell nearly 14% — a crash the wire services were calling the worst single day on record — with the selling heaviest exactly where we'd been looking. Nu, PagSeguro, Inter, XP: all marked down double digits. And StoneCo, the merchant-payments company we refused to buy on October 7th at the top of the first-round euphoria, traded at $7.38 in Monday's premarket — down more than 35%, almost exactly the "Lula-win washout toward the ~$9 low" we named three weeks in advance.
Tuesday's edition made it official: Buy, flagged at that premarket print.
Here's what happened next, because it's the whole lesson. By Monday's closing bell, StoneCo stood at $8.33 — about 13% above our flag. The deepest discount of the panic lasted roughly as long as a cup of coffee. A price you name before the panic is a price you can actually use during one.
Now the honest part. Brazil's selling didn't stop Monday: the Ibovespa fell again Tuesday and again Wednesday, closing at a two-month low, and Morgan Stanley and Citi were among the banks downgrading Brazilian assets outright. We could not verify a fresh StoneCo print past Tuesday's premarket ($8.52) by press time, so grade this one against Monday's close, not Thursday's tape — and expect it to swing with every headline out of Brasília until the economic team is named. The thesis never needed the election: StoneCo built its business under high-rate, high-drama Brazil. The kill is unchanged — the merchant-credit book souring — and the exam is November 12th. Size it like the volatile ticket it is. Still Buy.
2) The Checkbooks Stayed Open. The Crowd Sold the Store.
Wednesday afternoon the Fed held, and the argument moved to December — futures now price a December hike at better than 80%. Cboe, our Sunday Watch on the house that sells insurance against weeks like this, closed Monday at $335.25, up about 2% from the flag; its own report lands Friday morning, and with the midterms Tuesday, the calendar that justifies its premium is about to empty. The entrance is still a post-election calm near $300. Still Watch.
Then Wednesday night the AI argument got its widest data set yet. Microsoft beat everything — $4.89 a share, Azure up 48% — and Alphabet grew its cloud business 103%, booked that $561 billion backlog, and got marked down 11% Thursday over a miss built largely on an $8.7 billion paper markdown of its SpaceX stake. Between them: nearly $97 billion of capital spending in one quarter, with both promising more. Thursday's tape told you where the crowd stands — the Nasdaq fell 1.3% while the Russell 2000 rose 0.9%. The famous stocks had a worse Thursday than the average one. The spending is accelerating; the grading is getting meaner.
Our aisle caught the spending. Western Digital — Sunday's freezer-aisle Buy at the $345 Friday-morning flag — put together three straight green sessions: up 3.6% Monday to $356, 6.9% Tuesday, 3.2% Wednesday. Call it roughly 14% above the flag by Wednesday's close. The receipts kept arriving all week: a Monday Bank of America note said memory customers are "locking in supply for years at a time," and SK Hynix says its memory is sold out through 2029. Even the week's two target cuts — UBS to $435, Wells Fargo to $450 — landed above the price. The warning we attached still applies: memory is a cycle, and this one has already repriced violently once this fall. Still Buy.
Synopsys got its confirmation Monday night when Cadence — the other drafting table — beat and raised its full-year guide. Synopsys closed Monday at $454.33, up about 5% from Friday's flag. Still Buy. Modine caught Wednesday's loudest receipt: Vertiv, the data-center power-and-cooling bellwether, grew sales 61%, doubled its orders, and jumped 17% — and Modine rode toward $146 early Wednesday, about 7% above Tuesday's flag. The exam is Tuesday, and the margin question we flagged is the whole test. Still Buy. Nasdaq, Thursday's theater-sells-the-popcorn Watch, ended Tuesday at $104.36 — our flag, to the penny, which is to say it's done nothing yet. The entrance is still the mid-$90s or a sell-the-news debut. Still Watch.
And the fitting room finally let us in. FormFactor reported Wednesday night: record revenue of $280.5 million, up 38%, earnings of $1.04 against an 86-cent estimate, guidance above the Street — and a 10.5% after-hours markdown to $99.35, below even our August flag. That was the entrance we'd named twice, so Friday's edition flipped it from Watch to Buy. Then came the punchline: by Thursday midday the stock traded back near $111, above its pre-print close. The markdown lasted one evening. We'd been standing at the window since August 26th for exactly that evening. The crowd's reflexes are fast; its remorse is faster. Buy — upgraded this week, and we reaffirm it.
3) Report Cards: The Repriced and the Returned
Tuesday was the heaviest tape of the season — roughly a third of the S&P 500 reported this week — and our names sorted into the two piles we described Wednesday.
The repriced pile first. UPS beat for the fourth straight quarter, raised its guide again, and closed Tuesday at $106.09 — up 5.7% from the flag in a single session. The market spent two years pricing that 6.4% dividend as doomed; the new network just covered it, out loud. Still Buy. Centene deserves a correction note: Wednesday's edition said the crowd was taking profits at down 2%. By Tuesday midmorning the crowd had changed its mind — the stock traded at $71.24, up nearly 5%, pressing right against the $71.78 average analyst target. Our entrance was analyst targets resetting higher after the print; that's now the specific thing to watch, because the markdown-to-the-low-$60s door looks like it's closing. Still Watch.
Antero passed Wednesday night — earnings of $1.19 a share, well past estimates, on record production. It had already firmed to $41.54 by Monday's close, up about 3% from the flag, before the print even landed; the EQT–Range comp has the whole Appalachian street walking taller. Still Buy. Terex we flagged Wednesday at $49.51, after the market marked down its beat over cautious guidance; no fresh print verified by press time, but Herc's raised fleet budget — the thesis — didn't get cheaper to ignore. Still Buy. Hexcel likewise: flagged Tuesday at $78.90 after last week's 12% markdown of a 1% miss, no fresh tape we could verify by press, while its customers spent the week confirming the shipset math — Boeing's record $745 billion backlog chief among them. Still Buy.
Patrick Industries handed in its paper Thursday morning, right at our press time: sales of $975 million, but earnings per share down 37% to 64 cents. Half our entrance asked for margins holding — a 37% profit decline is not that. The other half asked for clarity on LCI, and that got a date: Patrick reaffirmed the merger after Monomoy's $101 cash gatecrash, LCI's board still recommends Patrick's deal, and shareholders vote November 18th. We'll let the aisle's cash comp argue with Patrick's income statement from the sidelines. Still Watch.
And Whirlpool, Wednesday's Sell for holders, promptly bounced — $27.31 by Wednesday's close, about 6% above the flag. We'll say it plainly: so far, the Sell is losing. We'll also say why we're not moving: a bounce doesn't print an E in the P/E, and the company is still guiding to a full-year loss while waiting on a housing thaw it can't schedule. Three service calls is still three service calls. Sell stands (for holders).
4) The $113 Barrel and the Waiting Room
The war premium breathed out a little this week — Brent eased from $115 Wednesday to about $113 by Thursday midday, with WTI just over $100 — but the floor under the barrel is the story, and OPEC+ meets Sunday with most members already pumping below their targets. Halliburton, Friday's barn-builder Buy, sat right at its $35.44 flag at Monday's close; nobody is paying for a drilling recovery yet, which remains the point. Still Buy. Viper, the landlord under the Permian, closed Monday at $47.16 — up about 4% from the flag, with the base dividend already raised 32% — and it hands in the first report card of our next exam week on Monday. Still Buy.
The waiting room held the rest. Robert Half kept running after we refused Friday's 13% pop: $45.87 by Friday's close, $44.98 Monday — roughly 6% above the flag we wouldn't chase. At 37 times trough earnings, the ticket price hasn't changed, and neither has our rule. Still Watch. Kinsale held near $370, a few percent below its pre-print close and nowhere near the low-$300s entrance; property premiums down 19.3% is still the real news in that release. Still Watch. Xylem we flagged at Tuesday's $92.86 wreck; no fresh print verified by press time, and the entrance is unchanged — orders converting to revenue, or the mid-$80s. Still Watch. Brookdale idled at $10.19 Monday, a touch above flag, while Welltower raised its full-year forecast Monday night — the neighborhood keeps filling in ahead of the November 5th exam. Still Buy. And Magna has no tape to grade at all: its first exam as Wednesday's Buy is Friday morning, which makes it yours before it's ours. Still Buy.
Before You Go
The scoreboard. Twenty-two calls this week — thirteen Buys, eight Watches, one Sell — including one in-week flip: FormFactor, Watch on Tuesday, Buy by Friday, when the entrance we named printed after hours and vanished by the next lunch. Through the freshest tape we could verify: Western Digital roughly +14%, StoneCo +13% from the panic flag, FormFactor +12%, UPS +5.7%, Synopsys +5.4%, Viper +4%, Antero +3.4%, Cboe +2.3%, Modine about +7% early Wednesday, with Nasdaq, Halliburton, and Brookdale flat at their flags. The tuition column: Whirlpool's Sell is 6% against us so far. The not-chased column: Robert Half (+6% past our no) and Centene (+5% while we watched) both ran without us — and we'd make both decisions again at those prices, because the one time this week the rule got its pitch, FormFactor, we swung. Not graded yet for lack of a verified fresh print: Hexcel, Terex, Xylem, Magna, Patrick. Older-card footnotes: Norwegian Cruise Line — the October 1st Watch — beat Thursday and jumped nearly 11% by midday, call it 14% above that flag, though the fourth-quarter guide came in light; we'll read the yield line before any upgrade, and grade it fully Sunday.
Your Monday checklist, in order. First, Friday's close: Magna's report card, Cboe's print, and Exxon and Chevron reporting into a $113 barrel. Second, Thursday night's papers — Amazon, Intel, and Sandisk, whose $44-to-$46-a-share quarterly guide is the memory boom's loudest claim yet; how Friday graded them grades our whole storage aisle. Third, OPEC+ meets Sunday — output steady is the expectation, and the floor under Halliburton and Viper is the stake. Fourth, the midterms are Tuesday, and the hedging calendar that justifies Cboe's premium starts emptying Wednesday; December's Fed meeting — a hike priced better than 80% — is the next appointment, December 9th. Fifth, next week's exams: Viper Monday, Modine Tuesday, Brookdale Thursday, and the October jobs report Friday.
Have a wonderful weekend.
Found this helpful? Share it with others.
Written by Behind The Markets