Five Warning Signs That Help Investors Separate a Value Trap From a Real Bargain
Every value investor wants to buy a good business at a low price. The hard part is telling a real bargain from a stock that is cheap for a reason. Learning how to spot a value trap helps investors avoid buying a weakening business just because its price looks low.
This article explains what a value trap is and why a low P/E ratio can mislead. It covers five warning signs, what a genuine value opportunity looks like, and a due diligence checklist. It also shows how Behind the Markets screens for traps.
💡QUICK ANSWER: HOW TO SPOT A VALUE TRAP
A value trap is a stock that looks cheap on measures like P/E but keeps falling because the business is weakening.
What Is a Value Trap in the Stock Market?
A value trap is a stock that looks undervalued on measures such as price-to-earnings (P/E), price-to-book (P/B), or EV/EBITDA. Its price, however, keeps falling or stalls for years. In a value trap vs value stock comparison, the key question is whether earnings can recover.
The danger of a value trap lies in its appearance of safety. Benjamin Graham popularized the 'margin of safety,' the idea that buying at a large discount to intrinsic value cushions against mistakes. That cushion works best when a company's earning power is stable or likely to recover.
If earning power is permanently weaker, the margin of safety can disappear. That is one of the classic Graham and Dodd value investing pitfalls, and it shows up in three ways:
Falling Intrinsic Value: If earnings shrink, the business's intrinsic value can fall faster than its share price. A 30% discount today can become full value tomorrow.
Cyclical Pause vs. Secular Decline: A cyclical downturn, such as lower steel prices in a mild recession, usually reverses with the economy. A secular decline, such as broadcast television losing viewers to streaming, may not.
Opportunity Cost: Holding a value trap for years can mean missing gains elsewhere while waiting for a turnaround that may not come.
Why Low P/E Ratios Can Mislead Investors
The price-to-earnings ratio is one of the most common valuation tools in financial media. It can also mislead, because it depends on earnings that may not last.
Low P/E ratio risks start with how the ratio is built:
Valuation Formula: Price-to-Earnings (P/E) Ratio = Current Stock Price ÷ Earnings Per Share (EPS)
Most free financial websites show the trailing twelve months (TTM) P/E ratio, which looks backward. When a business is being disrupted, analysts may cut their forecasts before the trailing multiple changes.
Consider a hypothetical value trap scenario:
The Optical Illusion: Industrial Corp trades at $60 per share and earned $6.00 per share over the past year. Its P/E ratio is 10x, which looks low.
The False Bargain: A competitor introduces a superior technology, and the stock falls to $30. A screener now shows a P/E ratio of 5x ($30 ÷ $6.00).
The Trap Closes: Two quarters later, Industrial Corp reports quarterly earnings. Earnings then fall more than 80%, to about $1.00 per share. At $30, the forward P/E ratio is 30x, not 5x.
What looked like a bargain was a stock trading at 30 times forward earnings. If the price then falls to $10, an investor who bought at $30 loses about two-thirds of the investment.
5 Warning Signs of a Value Trap
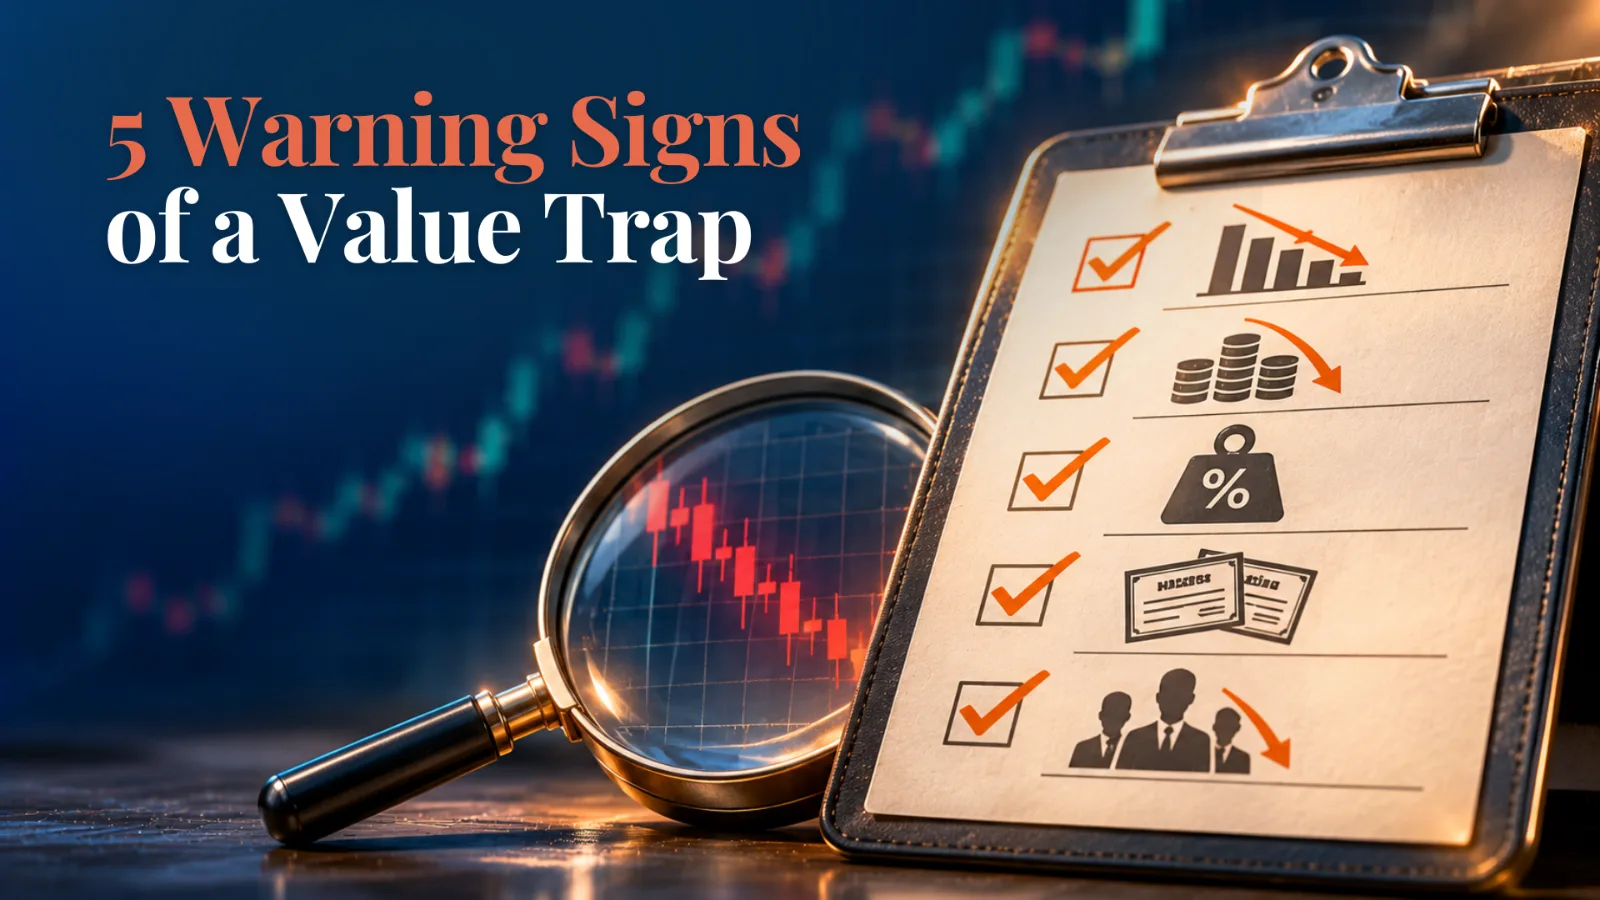
Identifying cheap stocks to buy means asking why they are cheap. Looking beyond headline multiples, these five warning signs can help investors spot a value trap:
1. Secular Industry Decline (Disrupted Business Models)
Value traps often appear in industries facing permanent, structural decline. When consumer habits, technology, or regulation shift for good, even leading companies may struggle to recover.
Examples: Department stores facing e-commerce, print newspaper losing advertising to digital platforms, cable providers losing subscribers to streaming, and combustion-engine parts makers facing electrification.
The Pricing Power Test: A healthy business can raise prices without losing many customers. A struggling one may see volumes fall even when it discounts, which can signal that demand has weakened.
2. Deteriorating Operating Margins Year-Over-Year
Management can sometimes hide a weakening business through acquisitions or heavy discounting that keeps revenue flat. Gross and operating margins are harder to hide over time.
Gross Margin Compression: Gross margin is gross profit divided by revenue. If it falls for three years in a row, the company may be losing pricing power and competing mainly on price.
Operating Deleverage: In businesses with high fixed costs, a small drop in revenue can cause a much larger drop in operating profit. This is called negative operating leverage.
3. Ballooning Debt to Fund Unsustainable Dividends
Some struggling management teams try to keep shareholders happy by paying dividends or buying back shares with borrowed money while cash flow shrinks.
The Borrowing-for-Payouts Red Flag: Watch for a Net Debt-to-EBITDA ratio above roughly 3.5x while free cash flow turns negative. If a company must borrow to pay dividends, a cut becomes more likely.
4. Chronic Share Dilution and Stock-Based Compensation
Companies under pressure sometimes issue more shares or grant large stock-based compensation (SBC) to executives, even while the stock price sits at multi-year lows.
The Cost of Dilution: Check the weighted average diluted share count over three to five years. If shares grow about 3% to 8% a year while revenue is flat or falling, existing shareholders are being diluted.
5. High Insider Selling Despite 'Cheap' Multiples
Insiders may know about customer orders and supplier issues before the public does. SEC Form 4 filings show their trades. These can offer clues, though insiders also sell for personal reasons such as taxes.
Words vs. Actions: If leaders call the shares a bargain but no insiders buy in the open market, that gap is worth noting.
Clustered Selling: When the CEO, CFO, and COO all sell large stakes near 52-week lows, it may suggest they see no near-term turnaround.
What a Genuine Value Opportunity Looks Like
A genuine opportunity looks different from a value trap. These companies often face temporary, fixable problems that have pushed the share price down.
A legitimate value stock typically shows these four characteristics:
1. Transitory, Fixable Headwinds
The earnings decline comes from a temporary event, such as a recession, an inventory cycle, a supply chain bottleneck, or a one-time legal settlement. Demand for the core product remains largely intact.
2. A Strong Balance Sheet
A company with low net debt, few near-term maturities, and healthy cash may be able to ride out a long downturn. It is less likely to need new shares or emergency funding.
3. Intact Economic Moats
Even in a downturn, the company keeps pricing power and high switching costs. Customers may delay upgrades, but they have a hard time moving to competitors.
4. Strong Historical Returns on Capital
Across past economic cycles, the company has generated returns on invested capital (ROIC) well above its cost of capital. Many investors look for ROIC of 12% to 15% or more.
Due Diligence Checklist: How to Spot a Value Trap Before Buying
Before buying a cheap-looking stock, investors can use this checklist to judge whether it resembles a turnaround or a value trap:
Step # | Due Diligence Check | Pass Requirement (Green Flag) | Fail Trigger (Value Trap Red Flag) |
|---|---|---|---|
1 | 5-Year Free Cash Flow Trend | Free cash flow roughly tracks or exceeds net income over five years | Free cash flow is negative or trails net income year after year |
2 | Gross Margin Stability | Gross margin is stable or expanding over 3 years | Gross margin has fallen by more than about 2 percentage points |
3 | Balance Sheet Solvency | Net Debt-to-EBITDA below about 2.5x; interest coverage above 5.0x | Net Debt-to-EBITDA above about 3.5x; large debt due within 18 months |
4 | Share Count Dilution | Diluted share count is flat or falling | Diluted share count grows more than about 3% a year |
5 | Insider Transaction Activity | Insiders buy shares in the open market (Form 4) | Several insiders sell large stakes, or hold very little stock |
6 | Industry Growth Outlook | Industry demand is growing or follows a normal cycle | Industry demand is in long-term decline |
7 | Valuation vs. History | Stock trades below its own 10-year median price-to-free-cash-flow multiple | Stock looks cheap only on peak trailing earnings |
Table 1: Due diligence checklist for investors. These are rules of thumb, not guarantees. A stock that fails several checks deserves a closer look before buying.
How Behind the Markets Screens for Value Traps
Mid-cap companies, with market capitalizations of $1 billion to $10 billion, often get less analyst coverage than mega-caps. That can leave some overlooked, though less coverage does not guarantee mispricing.
Behind the Markets, founded by Dylan Jovine, focuses primarily on mid-cap companies. Dylan has spent over three decades in the financial industry, including founding the brokerage firm Lexington Capital Partners. The research team looks at three areas when screening for value traps:
Solvency: We check whether a company could get through a long downturn without relying on new borrowing.
Competitive Position: We look for structural barriers to entry, such as patents, proprietary processes, regulatory licenses, or strong local distribution.
Management Alignment: We review executive pay and open-market Form 4 purchases, and look for managers whose wealth is tied to the stock.
💡 READY TO FIND UNDERVALUED MID-CAPS?
Looking for stocks that are cheap for temporary reasons, not because the business is weakening?
Behind the Markets provides monthly independent stock research focusing on overlooked mid-cap businesses with healthy balance sheets and durable moats.
Explore our undervalued mid-cap stock recommendations and our closed portfolio track record.
👉 Discover how Behind the Markets approaches value investing research.
Frequently Asked Questions (FAQ) About Value Traps
How can a stock with a low P/E ratio still be overvalued?
A low trailing P/E can mislead because it reflects past profits that may not last. Suppose a business earned $5.00 per share last year, but disruption will cut future earnings to $0.50. At $25, the trailing P/E is 5x, but the forward P/E is 50x. Valuation works best when based on likely future cash flows, not only past earnings.
Which financial signals can help spot a value trap?
One useful signal is the gap between free cash flow and net income. If a company reports profits but its free cash flow is negative or falling, accounting earnings may be hiding cash burn. Gross margin that falls for three straight years can also point to a weakening competitive position.
Can a value trap ever recover?
Sometimes, but it is uncommon. A recovery usually needs new leadership, the sale of weak businesses, and a healthier balance sheet. Betting on a turnaround without close knowledge of the company can carry high risk.
What is the difference between a cyclical stock and a value trap?
A cyclical company operates in an industry tied to the economy, such as semiconductors, copper mining, or commercial construction. Its earnings rise and fall, but demand usually returns in the next expansion. A value trap suffers from secular decline. Its customers are leaving for alternatives, so demand may not recover even in a strong economy.
Sources: Benjamin Graham and David Dodd, Security Analysis (McGraw-Hill, 1934). U.S. Securities and Exchange Commission (SEC), EDGAR database (Form 4 filings).
Disclaimer & Regulatory Disclosure: Behind the Markets is an independent financial research publisher, not a registered investment adviser or broker-dealer. The information contained in this guide is for general educational and informational purposes only and does not constitute individualized investment, financial, legal, or tax advice. Investing in equity securities, including value and turnaround stocks, carries substantial risk of capital loss. Past performance is no guarantee of future results. Always consult a licensed financial advisor before making any investment decisions.
Found this helpful? Share it with others.
Written by Research Team