Morning Watchlist: Saturday Edition
The Week in Review A quick note from Behind the Markets
It's Saturday morning, and this was the week corporate America aced the exam and got sent to detention anyway.
On Wednesday night, inside a single hour, Tesla, Meta, IBM, Texas Instruments, and Lam Research all reported. All five beat. By Thursday midday the Nasdaq was down about 2%, Lam had been marked down double digits, and Meta had given back nearly 6% the day after a record quarter and a 2-for-1 split. Meanwhile Brent crude pushed past $111 — a five-month high — the 10-year Treasury rallied to 5.02%, and jobless claims printed 194,000, the fewest in three months.
A working economy. Companies that keep beating. A market that keeps paying terrible exchange rates on fear.
Saturday is when we grade our own card against that tape: all nineteen calls from this week's editions, plus the open names whose exams landed. One press note, as always: we go to press Thursday midday, so Friday's session belongs to you, not to us — it's on your Monday checklist below. Four stops on the tour.
Let's get into it.
1) Exam Week, Graded in Red Ink
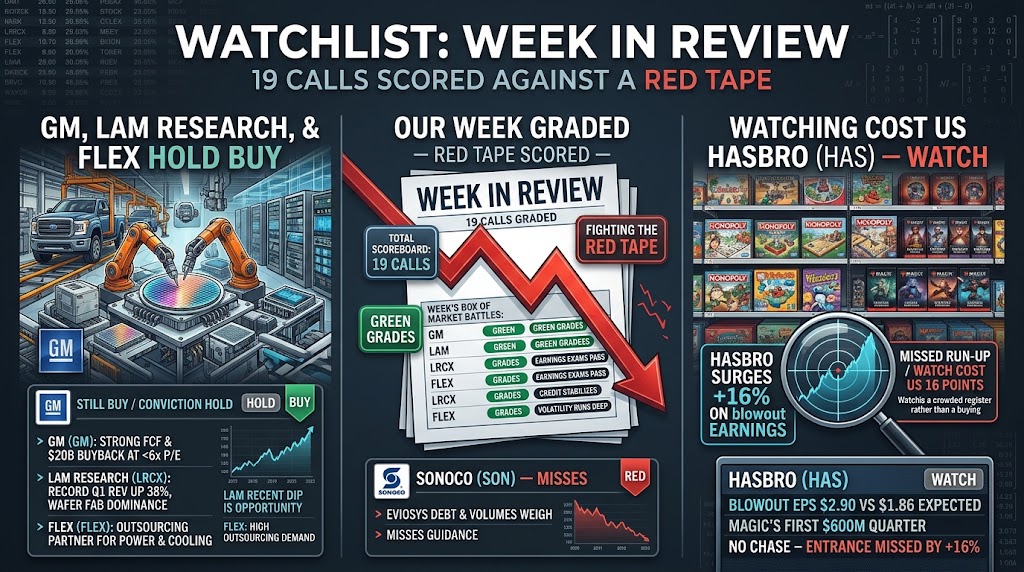
General Motors passed everything on Tuesday — $3.70 against $3.63, free cash flow guide raised, a new $20 billion buyback — and got grounded over a $2 billion commodity footnote. We bought the markdown Wednesday at roughly $76, and the stock closed Wednesday at $76.11. The family is still buying out the heirs while the appraiser sulks. Still Buy. One row over in the same aisle, Autoliv — the seatbelt that survives Wednesday's robotaxi argument — closed Wednesday at $115.94, right at Sunday's flag, with its own exam Friday morning. That grade is yours before it's ours; it leads your Monday checklist. Still Buy.
Steel Dynamics owed us an answer. Monday night it printed $5.26 — below the $5.34 to $5.38 it pre-announced in September — on record revenue of $6.51 billion and record shipments. We flagged the demerit midweek and promised Saturday would grade the tape. The tape shrugged: $247.97 by Wednesday's close, up 3% from Sunday's $240.76 flag. A company missing its own three-week-old guide is a yellow flag; a market that forgives it on record revenue is information too. The guide still annualizes near $21 a share. Still Buy.
AT&T passed its Wednesday exam loudly — 65 cents against 61, a record 769,000 internet additions, a raised full-year guide — and fell 6.4% that day anyway, to $21.91, on light phone adds, before steadying near $22.36 Thursday morning. That's about 5% below Tuesday's flag. The record adds still have a donor, and the donor's stock answered: Comcast, Thursday's Sell for holders at $22.36, closed Wednesday at $22.08. Still Buy on the taker. Sell stands (for holders) on the donor.
Sonoco is the week's honest failure. Thursday morning our Tuesday Buy handed in its paper and missed: adjusted earnings of $1.67 against $1.92 a year ago, the sales outlook cut, an $829 million goodwill write-down swinging the bottom line to a $732 million loss — and the stock fell about 10% in premarket trading, erasing its small gain over our $49.12 flag and then some. The culprit was partly weather — drought thinned the vegetable harvest, and unfilled cans don't ship. Our stated kill was volumes shrinking while the debt bill runs, and one drought quarter doesn't settle that question: management held the full-year earnings guide at $5.30 to $5.50, which puts the marked-down price near 8 times earnings with the dividend intact. We're wrong so far, and we say so. The next print decides whether this was weather or trend. Still Buy.
And the quiet A: PepsiCo, Monday's breakup trade, closed Wednesday at $134.70 — up 3.1% from the $130.66 flag. The market finally read the renewal paragraph. Still Buy.
2) The Margin Call Kept Billing the Cash Registers
October's argument — who pays for the AI build-out — spent another week marking down everyone who sells to it, even as the demand receipts piled higher: Super Micro's $4 billion revenue surprise, Meta's $135–145 billion shopping list, Lam's view of 2027 equipment spending above $200 billion.
Lam Research is Friday's flip, already graded twice. We moved it from Watch to Buy at Wednesday's $260.81 close after both named entrances printed — and Thursday the chip aisle opened red and Lam traded near $233 by midday, down about 11% on no news beyond a whisper miss and a nervous tape. At that price the stock costs roughly 25 times the pace of its own December guide, against 35 times forward when we refused to chase it at $328 three weeks ago. The toll road keeps getting cheaper while the traffic forecast rises. Still Buy.
Flex, Friday's other headline pairing, was marked down before the ink dried: $79.25 by Thursday midday against the $92.80 flag — about 15% of tuition in days, almost all of it the same AI-financing tape. Nothing about the thesis moved: the Axiom appraisal is still $37.5 billion, and the gap between the guest cottage and the whole property's asking price only widened. The exams are dated — earnings Wednesday, Investor Day November 10th. Still Buy.
Dycom took similar treatment: $237.45 by Wednesday's close, down about 8% from Monday's flag, on no company news we could find. The record $12.2 billion backlog didn't shrink; the multiple did. There's still no DRAM on a ditch digger's bill of materials. Reports around November 18th. Still Buy.
The green register in the aisle was TD SYNNEX — $251.14 Wednesday, up about 2% from Thursday's repeat flag, riding the Super Micro receipt it was paired with. Still Buy. Hudbay held at $24.08, a touch above flag, though note Thursday took gold down 2% to $4,068 — the by-product sweetener softened even as copper's story held; Freeport, the aisle's bellwether, reports Tuesday. Still Buy. Belden we can't fairly grade: the shelf is so dim we couldn't verify a fresh print by press time — the latest verified quote, $102.83, predates Wednesday's flag. The order book is the thesis and the report is Thursday the 29th. Still Buy.
One more register rang. Moody's — our October 6th Buy at $441 — printed Wednesday with investment-grade issuance up 18% on AI and hyperscaler borrowing, reaffirmed its guide, and closed at $481.05, up about 9% from the flag. Every IOU in a land rush needs a grade. Still Buy.
3) What Watching Cost This Week
Last Saturday, the watch column paid for the whole page — Entegris fell 12% while we stood outside. This week the column sent us the bill instead.
Hasbro's Tuesday print was the blowout we said it might be — $2.90 against $1.86 expected, Magic's first $600 million quarter, the holiday guide raised, the buyback target doubled — and the stock ran straight past our entrance: $109.52 Tuesday, $114.00 Wednesday, nearly 16% above the $98.41 flag. The saner price never came. Watching cost sixteen points, and we're writing that number down in the same ink we used for Entegris. The rule hasn't changed since the Burlington call in August: a miss you can buy is worth more than a beat you have to chase. If it keeps running, we let it go. There's always another rack. Still Watch.
The rest of the column ran too, just slower. Netflix recovered to $67.36 by Thursday midday — above the $64.50 panic flag, nowhere near the high-$50s entrance; the 57-to-1 exchange rate on fear lasted about 48 hours. Still Watch. Match closed Tuesday at $46.53, up 5.5%, with the November 2nd print still the entrance. Still Watch.
Valero is the one we owe you a straight answer on, because we said the entrance was Thursday's print — and the print was a monster. Adjusted earnings of $23.90 a share, against roughly $21 expected and $3.66 a year ago, on a refining margin of $39.24 a barrel versus $13.14 last year. The stock jumped about 5% in premarket trading. So why aren't we buying? Because the quarter proves the spread exists, not that it lasts — and we rang the register on PBF two weeks ago for exactly this reason: peak-spread earnings sitting in the crosshairs of five Washington programs built to crush them. Buying one refiner at record cracks while selling another would be having it both ways. The print passed; the thesis didn't change. Still Watch — and if the spread outlasts the campaign, we'll have been wrong in public, at record prices.
FirstCash split the difference. The pawn counter is booming — revenue up 18%, pawn earnings up 28%, the dividend raised 10%, and a 5% premarket pop Thursday — but the other half of the company went the other way: the payment-plan arm's income fell by roughly a quarter on merchant bankruptcies. A booming counter, a shrinking back office, and a still-crowded register. Still Watch.
4) The Ocean's Invoice Came Due
The week's quietest repricing happened on the water. Drones reached Shaybah and Dammam on Wednesday, the State Department ordered non-emergency staff out of Saudi Arabia, and by Thursday Brent sat above $111 with WTI near $98 — five-month highs — while supertanker rates held near $1.3 million a day.
International Seaways, Friday's flip from the August watch, was flagged at Wednesday's $111.15 close, so there's no tape to grade yet — just the arithmetic: the fleet is still billing last winter's rents, and every renewal reprices into Thursday's ocean. Still Buy. The kill is still a signature in Tehran.
The airlines showed both sides of the same bill. United closed Wednesday at $101.67 — up nearly 6% from the flag, the market paying for record demand even after the fuel miss. Our entrance asked for demand holding and the fuel bill cresting; we got half. Still Watch. Alaska Air, the fuel-side name we've watched since August, showed what the other half looks like: Tuesday's report turned 14% revenue growth into an adjusted loss, with fuel up 60% to $3.94 a gallon and the fourth quarter guided to $4.65 to $4.85. That income statement is the watch column's whole purpose, printed. Still Watch. And Knight-Swift — the borrowed-barrel Watch from October 6th — passed its exam with $0.83 against $0.32 a year ago and a CEO calling for "further meaningful rate growth" in 2027; the freight recovery is arriving, but at about $63 it was already priced on the ticket. Still Watch.
Expedia, the commission collector we bought Thursday precisely because it has no fuel bill, got marked down with the travel aisle anyway: $285.64 Wednesday, back to $293 by Thursday midday, about 3% below flag. The proof has a date: November 4th. Still Buy.
Before You Go
The scoreboard. Nineteen calls this week — fourteen Buys, four Watches, one Sell. Through Thursday midday, the Buy column read: PepsiCo +3.1%, Steel Dynamics +3.0%, TD SYNNEX +1.8%, Hudbay +0.7%, with GM, Autoliv, and International Seaways at their flags; tuition ran at Expedia (-2.6%), AT&T (-4.6%), Dycom (-7.9%), Sonoco (roughly -9%), and the two newborns the AI tape met first — Lam (-11%) and Flex (-15%). Belden we couldn't fairly price. The Sell worked quietly: Comcast -1.3%. And the watch column ran without us — Hasbro +16%, United +6%, Match +5.5%, Netflix +4.4% — four entrances named, none printed, none chased. Last week watching saved 12 points; this week it cost 16. Same rule both weeks. We pay the rule's price because, over enough weeks, the rule pays ours. Older-card footnotes: Moody's +9% on a clean print, First American's commercial revenue grew 21%, and Lithia and Verizon were graded in Friday's edition.
Your Monday checklist, in order. First, Friday's close: Autoliv's Friday-morning report — the seatbelt's own exam, consensus $2.26 — plus SLB, and whether Thursday's chip-aisle selloff held or snapped back through Lam and Flex. Second, Deckers reported after our Thursday press time; grade it against the $79.08 October flag. Third, tomorrow Brazil votes — StoneCo's named entrance, win or washout. Fourth, Tuesday and Wednesday bring the main event: a live Fed meeting with hike odds near a coin flip since the hot CPI, Freeport's report Tuesday, and Flex's earnings Wednesday. Fifth, Thursday the 29th stacks our deepest exam day yet: Belden, FTI Consulting, Tenet, and PBF — the referee's whistle on the refinery spread.
Have a wonderful weekend.
Found this helpful? Share it with others.
Written by Behind The Markets