Morning Watchlist: Wednesday Edition
A quick note from Behind the Markets
On Tuesday, corporate America brought home a stack of report cards. General Motors beat on everything that matters and raised its cash-flow forecast. GE Aerospace beat and raised. Hasbro beat by a dollar a share. Synchrony, Ally, and Western Alliance — three lenders the market keeps waiting to catch a cold — all passed their credit exams.
And the market took out a red pen anyway. GM dropped 8% in early trading. The chip aisle opened red again. Seoul fell another 3.65%.
When good quarters get graded like bad ones, the grading itself is the opportunity. Three stories this morning. Three pairings.
Let's get into it.
1) Straight A's, One B — Grounded Anyway
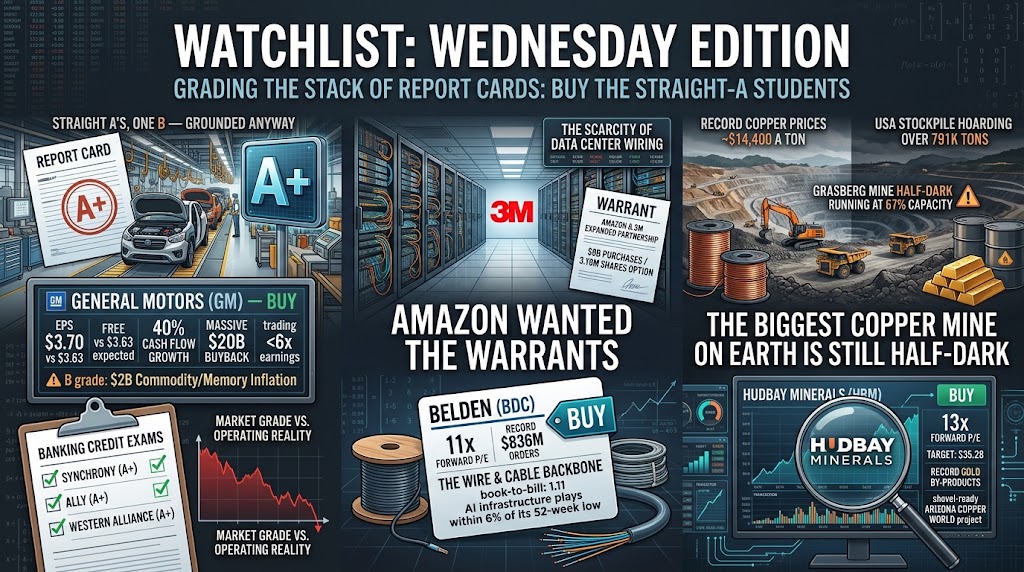
Start with the quarter. GM earned $3.70 a share against the $3.63 expected, on $50 billion of revenue. North American operating profit rose 43%. Free cash flow rose 40%, and the full-year free-cash-flow guide was raised by $2 billion. Then the board approved a new $20 billion buyback — on top of the just-finished $6 billion program that already shrank the share count 6% in nine months, from 904 million shares to 849 million.
And the stock fell 8% Tuesday morning, to around $76.
Why? The footnote. GM now expects about $2 billion of commodity inflation — and listed memory chips among the culprits, the same AI-driven memory squeeze Ericsson warned about last Thursday, now showing up on a truck's bill of materials. US deliveries slipped 5.5%, market share eased to 16.1% from 16.8%, and the profit guide's midpoint stayed put.
Tuesday graded a report card full of A's on its one B — and grounded the student.
The pairing:General Motors (GM) — Buy
Yes, the headline company — pairing strength earns the exception, the way it did with Constellation Brands and PepsiCo. At roughly $76, GM trades under 6 times the midpoint of its own freshly narrowed earnings guide of $12.75 to $13.75 a share. The S&P 500: about 21. (Ignore the trailing P/E near 42 — it's distorted by past special charges; the guide is the real number.) The average analyst target sits at $104, about 37% above Tuesday's marked-down price.
And then there's the buyback. Twenty billion dollars against a company marked down to roughly $67 billion is an authorization to retire more than a quarter of the shares outstanding — a family quietly buying out the other heirs while the appraiser is in a bad mood. The Wall Street Journal reports executives consider the stock undervalued; Tuesday handed them a better price within hours.
The honest risks: the $2 billion cost headwind could grow — memory prices are still climbing; US share is slipping while deliveries fall; and GM Financial's earnings dropped 17% in a 7%-car-loan world. The kill: deliveries down 5.5% hardening into a demand break — a buyback shrinks the share count, but it can't outrun an empty showroom.
2) Amazon Wanted the Warrants
Here's a sentence nobody had on their 2026 card: 3M is an AI stock now.
Late Monday, 3M expanded its data-center partnership with Amazon — optical connectivity and other data-center products — in a deal that fully vests once Amazon's purchases reach $6 billion. The tell is the structure: Amazon took a warrant for 3.16 million 3M shares at $164.89, exercisable over seven years. The stock jumped 5% in extended trading, then 3M beat Tuesday's earnings ($2.50 versus $2.29 expected) and raised its outlook for good measure.
Read the warrant the way we read insider buying. When the biggest buyer on Earth demands equity upside in its supplier before committing $6 billion, the supplier's product is scarce — and the scarcity has moved past chips, past power, down into the century-old industrial aisle: connectors, cable, cooling, tape.
A data center, after all, is mostly a building full of wiring. The market keeps bidding on the chandeliers. Nobody tours the wall sockets.
The pairing: Belden (BDC) — Buy
Belden has made wire and cable since 1902 — today it's the connectivity and networking gear inside factories, utilities, and data centers, exactly the aisle Amazon just wrote into a $6 billion contract with 3M. Second-quarter orders hit a record $836 million, up 19%, book-to-bill 1.11, and the CEO said AI data-center investments are "beginning to show up in our order book."
At $103.67 as of Monday's close, the $4 billion company trades at about 11 times next year's expected earnings against the S&P's 21 — within 6% of its 52-week low, down 35% from its high. All five covering analysts rate it a Strong Buy, with an average target of $153, nearly 50% above the price.
Why it's cheap, honestly: October's AI-financing panic has been selling everything that touches the build-out, and Belden's GAAP earnings look muddy right now — the RUCKUS Networks acquisition it closed in July layers on purchase-accounting noise (GAAP guided near 80 cents this quarter while adjusted earnings run near $2.25 — the Jackson/Global Payments distortion). Only five analysts cover it, so the shelf is dim. And section three's record copper is Belden's input bill — one aisle's record is another aisle's invoice. The kill: the order book rolling over — book-to-bill under 1 means the rewiring paused. It reports October 29th.
3) The Biggest Copper Mine on Earth Is Still Half-Dark
Quietly, while the market argued about AI financing, copper has been setting records — trading around $14,400 a ton. On Monday, Goldman Sachs raised its end-2026 forecast to $14,700 a ton, from $13,735, citing shrinking mine supply outside the US and deficits — demand exceeding supply — for the next couple of years.
Two forces are squeezing the same metal. Supply: Grasberg in Indonesia — the world's biggest copper-gold mine, owned by Freeport-McMoRan — still runs at about 67% of its old rate after last year's disaster, and Freeport says full capacity won't return until the end of 2027. When the biggest farm in the county floods, every other farmer gets the harvest price. And hoarding: buyers have stuffed US warehouses with 791,679 short tons of copper ahead of possible import tariffs — stockpiling that makes America look supplied while the rest of the world runs lean.
Copper is the plumbing of electricity. Every data center, grid upgrade, and EV is a building full of copper pipe — and the pipe price just hit a record while the biggest pipe factory is half-shut.
The pairing: Hudbay Minerals (HBM) — Buy
Freeport is the obvious ticket, but the crowd found it — the target raises are chasing the tape (Barclays to $84, JPMorgan to $92) with its own report due next Tuesday. One shelf over sits Hudbay: copper and gold from Manitoba and Peru, plus Copper World in Arizona — a shovel-ready American copper project in the exact world where buyers pay a premium for metal already inside the tariff wall.
At $23.92 as of Monday's close, the $10.6 billion company trades at about 13 times next year's expected earnings — against the S&P's 21 — with trailing earnings per share up 136%, and record gold sweetening every ton as a by-product. Twenty-three analysts rate it Strong Buy; the average target of $35.28 sits 47% above the price, and it's about 26% off its 52-week high.
The honest flags: the stock is up more than 65% off its low — we're not early; Scotiabank and Barclays trimmed estimates into the November 12th report on no news we could find; the dividend is a rounding error; and Peru is Peru. The kill is Goldman's own caveat: if the tariff never lands, the US stockpile unwinds and those 791,679 tons hit the market first — a 13x miner only stays cheap if the metal holds.
Before You Go
That's the watchlist: a $20 billion buyback marked down 8%, the warrant Amazon demanded from a 124-year-old industrial, and record copper with the biggest mine half-dark. One theme, as always: when the market grades every report card on one footnote, buy the straight-A students it fails.
Now, Tuesday's exams — the credit desk swept. Synchrony earned $2.68 against the $2.48 expected with charge-offs improving to 4.79% and purchase volume up 8%. Ally earned $1.34, up 16%, on record applications with charge-offs flat. Western Alliance earned $2.45 with its margin up and charge-offs down to 0.30%. All three Buys stand. Hasbro was the blowout — $2.90 against $1.86 expected, Magic's first $600 million quarter, guidance raised — but the stock rose to about $100, not the saner price our entrance requires; still Watch, no chase. One demerit: Steel Dynamics printed $5.26, below the $5.34–5.38 it pre-announced in September — record $6.5 billion of revenue, but a company missing its own guide gets flagged; Saturday grades the tape. And a calendar note: Reuters reports OpenAI racing to lock in commitments above a $1.4 trillion valuation before Anthropic's debut — now expected mid-November, not October. The stadium's marquee ticket moved; it didn't vanish.
This morning, AT&T and Sonoco take immediate exams, with can-maker Crown Holdings' soft fourth-quarter guide as the aisle's warm-up. And tonight is the week's main event: Tesla, Meta, IBM, Texas Instruments, Lam Research, and Crown Castle all report within an hour of the close — two of them ours, with Knight-Swift, First American, Moody's, Lithia, and CME filling out the day.
Found this helpful? Share it with others.
Written by Behind The Markets