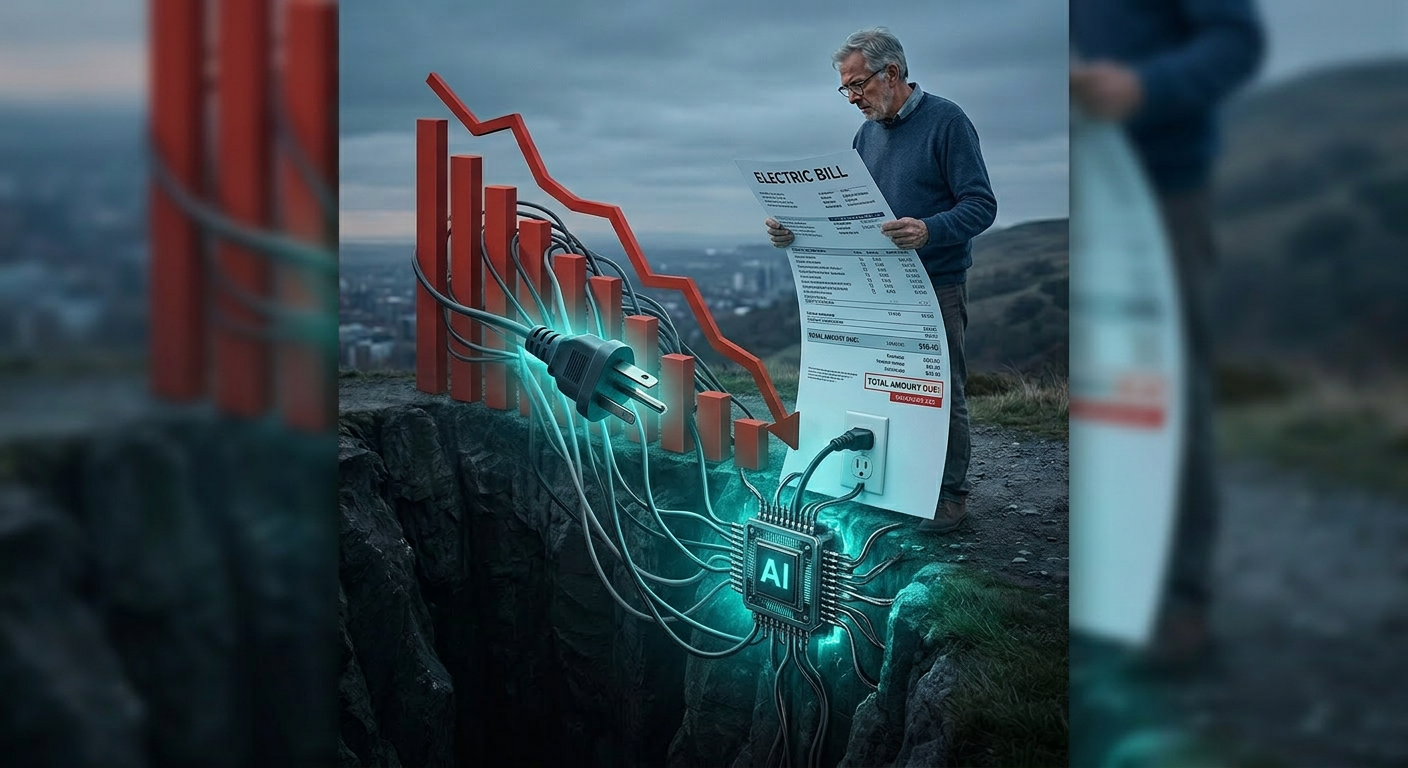
Your Electric Bill Just Became an AI Tax. Residential Rates Are Up 36%. And 27 States Are About to Fight Back.
A quick note from Behind the Markets
Wall Street wants you to believe the AI boom is "free." Just buy the megacaps. Let the machines print money.
But the real bill shows up somewhere else. It shows up on your electric meter.
1) AI Data Centers Aren't Just a Tech Story — They're a Regulated Monopoly Story (and Ratepayers Are the Exit Liquidity)
A new Earthjustice/Synapse report just exposed something most investors haven't confronted: the AI boom isn't just consuming electricity. It's being subsidized by your neighbor's electric bill.
Mississippi's SB2001 lets utilities sign "secret contracts" with data centers — shielded by nondisclosure agreements — while limiting the oversight role of the Public Service Commission. Synapse estimates Entergy Mississippi's residential customers are already paying roughly $10.60 more per month because of grid investments tied to data center load. That's $38 million paid by residential ratepayers as of March 2026, with $74 million projected by year-end.
Mississippi isn't an outlier. It's a preview.
Residential electricity prices across the U.S. have risen 36% since 2020 — from 12.76¢ to 17.44¢ per kilowatt-hour — and the EIA projects they'll hit 19.01¢ by September 2027. In Virginia, Dominion Energy petitioned for a 15% base rate increase over two years and projected the average residential bill will rise 50% by 2039 — citing data center demand. In Columbus, Ohio, monthly bills are increasing $27. A 40-year Virginia homeowner's bill jumped from $100 to $281 in a single month.
The new generation of AI data centers isn't comparable to what came before. 90% of existing data centers use less than 50 megawatts. The new AI complexes demand 1,000 to 4,000 megawatts — one to four gigawatts each. The IEA projects global data center electricity consumption will exceed 1,000 TWh by end of 2026 — equivalent to Japan's entire annual electricity usage.
The political backlash has arrived. Lawmakers in 30+ states have introduced over 300 bills targeting data centers — including moratoriums, tax incentive clawbacks, and energy policy reforms. 27 states are considering legislation requiring data center developers to bear the full cost of new energy infrastructure. The White House held a "Ratepayer Protection Pledge" signing on March 4 — but it's nonbinding, and MultiState reports it "does not appear to have stalled state legislation."
One company that benefits from the regulated capex boom regardless of who pays:
Company: Eaton Corporation (SYM: ETN)
The global power management leader — manufacturing switchgear, transformers, circuit breakers, and power distribution units. The physical equipment every data center and grid upgrade requires.
Eaton doesn't care who pays the bill — the data center or the ratepayer. It gets paid for the equipment. When utilities spend $1.4 trillion over five years on grid upgrades, when half of U.S. data centers are stalled by electrical equipment shortages, and when transformer lead times stretch to 3–5 years, the company that manufactures the hardware has pricing power that exists independently of the political fight. Revenue growing mid-teens, record backlog, electrical segment fastest-growing. Eaton is the toll road of the AI power buildout.
Bottom line: The AI boom is becoming a utility-rate story. Watch where the cost gets pushed. When you see secrecy plus capex, you're looking at the next fight over who pays.
2) The Best AI "Picks and Shovels" Might Not Be Chips — It Might Be Wires, Transformers, and the Companies That Can Deliver Power on Time
The market is obsessed with Nvidia, AMD, and whatever buzzword comes next. But data centers have a hard constraint: you can't run racks on vibes.
Half of U.S. data centers planned for 2026 are delayed or canceled — not for lack of money, but because the specialized electrical equipment isn't available. Transformer lead times stretched from 24–30 months pre-2020 to 3–5 years today. Only 5 GW of 12 GW announced capacity is under active construction. The $1.4 trillion utility buildout is real. The 18–20 Bcf/d of new Gulf Coast pipeline capacity being built in 2026 — the largest in a decade — feeds the gas that powers the data centers.
And this is where Wall Street gets sloppy. They assume power is infinite. They assume the grid is "someone else's problem." For retail investors, that blind spot is the opportunity.
The winners aren't just utilities. They're the underfollowed layer: equipment suppliers tied to grid upgrades, companies building the substations and interconnections, and the pipeline operators moving the natural gas that fires the turbines.
This is also a political trade. When households see $281 electric bills and 27 states start passing "large load" legislation, the companies that can structure contracts so the data center customer pays its share — rather than socializing costs — will be the ones with constructive regulatory relationships.
One company positioned as the toll road between the gas supply and the data center power stack:
Company: Williams Companies (SYM: WMB)
The largest U.S. natural gas pipeline operator — 33,000 miles of pipe, ~30% of all U.S. natural gas, with the Transco system running directly through the corridor where data centers and LNG terminals are both demanding more gas.
Williams yields approximately 2.8% and gets paid on volume, not commodity price. When data centers need gas-fired generation and LNG terminals need feedstock simultaneously — and both are being built on the Gulf Coast and Eastern Seaboard — Williams' infrastructure becomes the critical path for both. The company doesn't need to win the political fight over who pays the electric bill. It just needs the gas to flow.
Bottom line: AI capex is turning into grid capex. The next "AI trade" could be the unsexy companies that physically move electrons — and the molecules that generate them.
3) Macro Hook: Yields Are Rising Again, and the Market Is Still Underpricing the Inflation Tail Risk
Thursday's GDP second estimate and Core PCE just hit the tape this morning. Treasury yields rose overnight as the market positioned for the data — the 10-year near 4.49% and the 2-year around 4.05% [VERIFY: update with actual Thursday print].
Here's why this matters in an AI/data center context:
AI is capex-heavy. It's power-hungry. And it pushes demand into hard assets — copper, transformers, concrete, gas turbines. That's not automatically "deflationary." Not in the real economy.
The $1.4 trillion utility buildout generates demand for real materials and real labor. Residential electricity prices are already up 36% since 2020. The EIA projects further increases. And the $635–$700 billion in hyperscaler capex is competing for the same construction crews, equipment manufacturers, and grid capacity that utilities need.
When yields are pressing higher and inflation prints are still the market's obsession, anything with long-duration cash flows gets repriced. That includes high-multiple AI "stories" trading at 30–50x earnings. Meanwhile, regulated infrastructure names — where cash flows are shorter-duration and indexed through rate cases — can hold up better because their revenue adjusts with the inflation they're causing.
One ETF that captures the infrastructure layer with inflation-linked revenue:
ETF: Utilities Select Sector SPDR Fund (SYM: XLU)
The benchmark utilities sector ETF — holding the regulated companies whose rate base expands with every grid investment and whose revenue adjusts through rate cases.
XLU has been underperforming because rising yields compete with utility dividends. But if the AI power buildout is real — and $1.4 trillion in planned investment says it is — then utility rate bases are expanding at a pace not seen in decades. When rate bases expand, regulated earnings expand. When regulators approve the capex (and 27 states are now fighting over the terms, not the principle), the revenue follows. XLU is the play for investors who believe AI is an infrastructure story, not a software story — and who want the cash flow that adjusts with inflation rather than getting crushed by it.
Bottom line: If yields keep creeping up, the AI hype trade gets harder. The AI infrastructure trade gets more interesting.
Before You Go
Who do you think wins politically when the grid needs billions in upgrades?
The data center that can hire lobbyists… or the household that gets a bigger bill?
That answer will shape the next leg of the AI trade.
Found this helpful? Share it with others.
Written by Behind the Markets