Friday delivered the single most important economic number of the month, and the market's response was to sell.
August nonfarm payrolls came in at 162,000, against a consensus that clustered somewhere between 53,000 and 65,000 depending on which survey you use. That is roughly triple the forecast, and it topped every single estimate in Bloomberg's survey of economists. The unemployment rate held at 4.1%, the lowest reading since June 2025.
Two months of bad labor data were also revised away. July's previously reported loss of 23,000 jobs became a gain of 21,000, and June was revised up from 20,000 to 31,000 — a combined 55,000 upward revision. The three-month average of monthly job gains jumped to 71,000 from 38,000.
Stocks fell anyway.
Why good news was bad news
The problem is which Fed this data lands on.
The FOMC meets September 15–16 with the funds rate at 3.50%–3.75% and a chair, Kevin Warsh, who has said repeatedly that inflation — not employment — is the central bank's predominant concern. Twelve-month PCE inflation is running at 3.7%.
For the past two months, the case against a September hike rested almost entirely on a visibly deteriorating job market. Wednesday's ADP report showing just 38,000 private jobs added supported that view. Thursday, Fed Governor Christopher Waller said he could support holding rates steady if inflation continued to ease, and hike odds fell to a coin flip. Stocks had their best day in a month on that comment.
Friday's report took the labor-market argument off the table.
CME FedWatch odds of a 25-basis-point September hike moved to roughly 60%, from about 50% the day before
The two-year Treasury yield rose to 4.38%, its highest level since January 2025
The 10-year traded near 4.78%; the 30-year near 5.24%
Gold slid from $4,490.89 to $4,365.57 before recovering part of the drop
Bitcoin, and most of Thursday's high-beta winners, reversed
It was not a clean hawkish print, which is why the reversal was orderly rather than violent. Average hourly earnings rose 0.3% month over month but decelerated to 3.1% year over year — the slowest wage growth since May 2021. The unemployment rate did not fall. And the household survey showed the labor force expanding by 683,000 people, the largest population-adjusted increase since October 2020, with participation ticking up to 61.6% from 61.4%. More people came looking for work and found it. That is supply meeting demand, not an overheating economy bidding up wages.
Still, one strong month after a weak summer changed the arithmetic. Next week's PPI and CPI reports now decide the meeting. That was the setup we flagged when the week's bills started coming due.
Tesla's robotaxi moment came and went
The day's biggest single-stock story had nothing to do with the Fed.
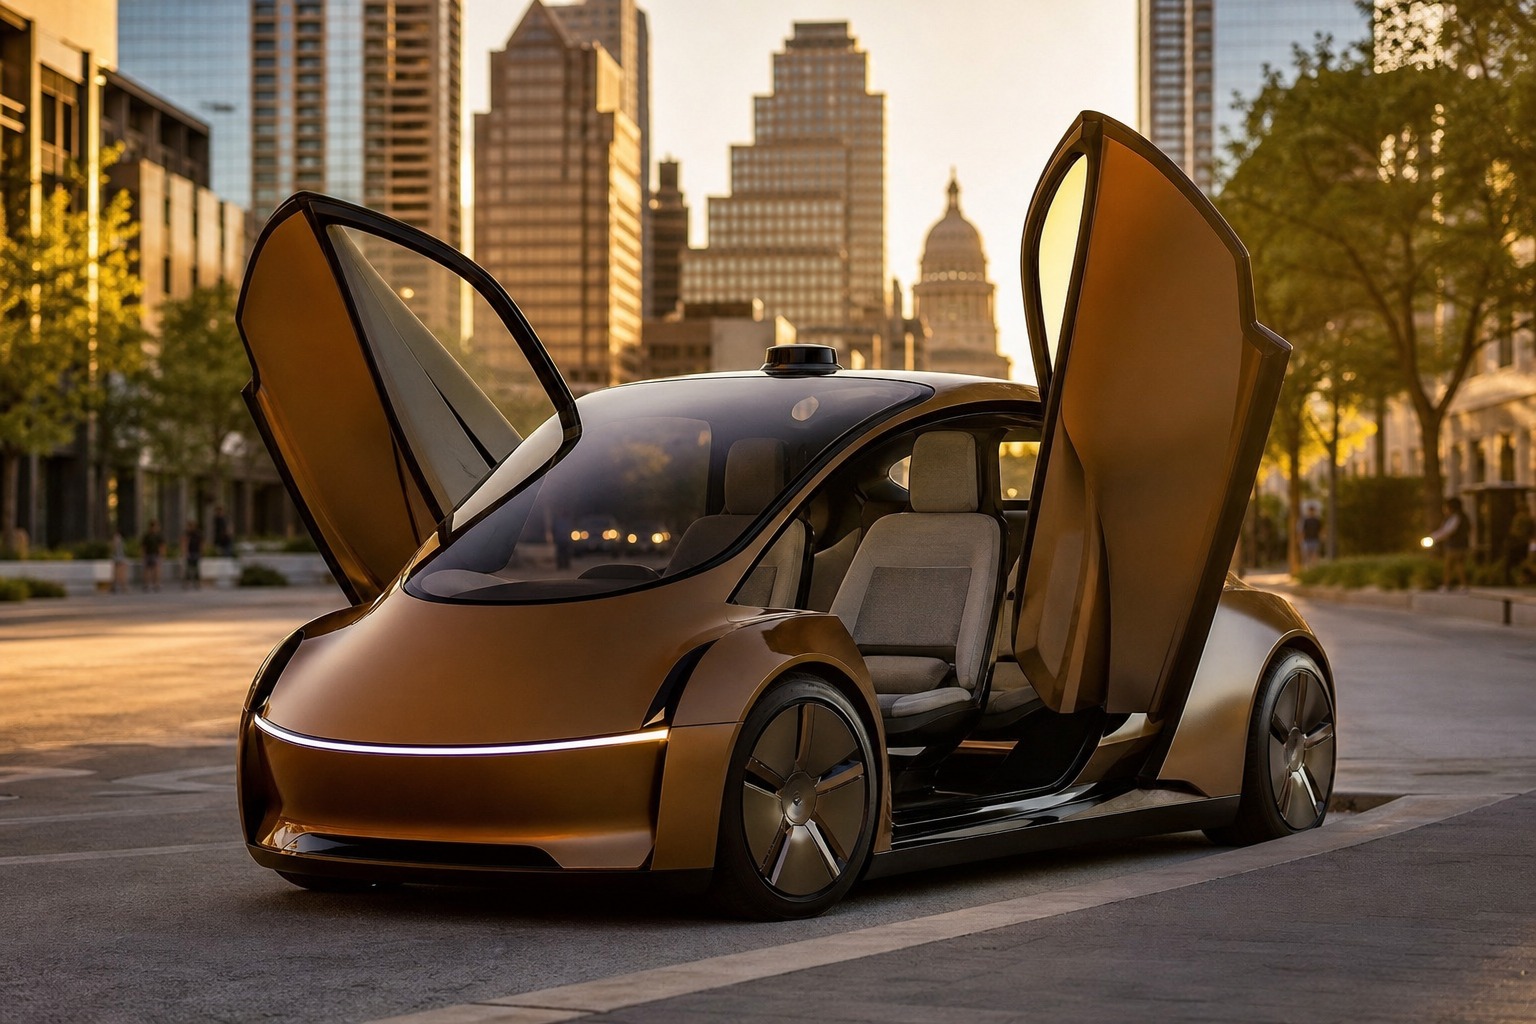
Tesla (TSLA) shares fell 5.9% to $354.08 after the company's long-awaited Cybercab update landed with a thud. The event, held Thursday in Austin, was invite-only, was not streamed, and CEO Elon Musk never appeared. The company said riders in its Robotaxi app can now hail a driverless Cybercab inside a geofenced area around Austin.
What Wall Street wanted was specifics. What it got, per RBC Capital Markets, was "limited new incremental disclosure relative to prior announcements, with key outstanding questions around pricing, production cadence, and regulatory approvals remaining open." Wells Fargo published a note headlined simply "TSLA Cybercab Launch Event Underwhelms," and flagged that the Austin service is "facing early execution issues" — users have posted about routing errors, missed destinations and long wait times.
Then the regulator showed up. The National Highway Traffic Safety Administration opened an "audit query" into whether Tesla properly self-certified the Cybercab — a purpose-built, two-seat vehicle with butterfly doors and no steering wheel or pedals — as compliant with federal motor vehicle safety standards.
Context matters here: the stock had risen 5.4% Thursday going into the event. Friday's decline erased that and more. This has been the recurring pattern in the robotaxi story since Musk began framing Tesla's future around robots rather than cars — the vision gets priced in, the execution timeline slips, and the stock re-rates back down.
Where the tape closed
S&P 500: 7,718.60, down 29.11 points, or 0.38%
Dow Jones Industrial Average: 53,414.25, down 271.86 points, or 0.51%
Nasdaq Composite: 26,506.99, down 77.07 points, or 0.29%
VIX: 14.53, up 1.47% — still historically low
Two-year Treasury yield: 4.38%, the highest since January 2025
For the week, the S&P 500 finished essentially flat — up about 0.1% from last Friday's 7,711.76 — after a round trip that included a 0.7% drop Tuesday, a 1.1% rally Thursday and Friday's giveback.
Individual names told a more dramatic story than the index. lululemon closed at $100.61, down 17.38%, following Thursday night's guidance cut. Snowflake gave back a chunk of its post-earnings surge, closing at $337.18, down 5.41% — profit-taking rather than any change in the business, since the fundamentals had not moved overnight. Zscaler fell 4.50% to $169.80 as the market digested a fiscal 2027 growth framework in the mid-teens. Apple dropped 2.51% to $319.97. On the other side, Ciena rose 1.12% to $321.00, recovering part of Thursday's 10% decline, and Nvidia added 0.84% to $230.36. The broader upgrade cycle is still running, as Friday's list of freshly upgraded names showed.
What lands next
Markets are closed Monday, September 7, for Labor Day. When they reopen Tuesday, the calendar tightens fast:
Thursday, September 10: August PPI, plus earnings from Oracle and Adobe after the close
Friday, September 11: August CPI — the last inflation reading before the Fed meets
September 15–16: FOMC decision
Friday's jobs report did not settle the rate question. It moved the burden of proof onto the inflation data. If CPI comes in hot on top of a 162,000 payroll print and an ISM services prices index at a four-year high, a September hike becomes the base case rather than a coin flip. If it cools, the argument reopens.
Two data points, one week, and a Fed meeting on the other side of them.
This article is for informational and educational purposes only and does not constitute investment advice or a recommendation to buy or sell any security.
Found this helpful? Share it with others.