The Show Is CPI and Bank Soundbites. The Signal Is Deposits, Credit, and Regionals.
A quick note from Behind the Markets
Wall Street spent yesterday obsessing over the CPI print and big-bank soundbites. That's the show.
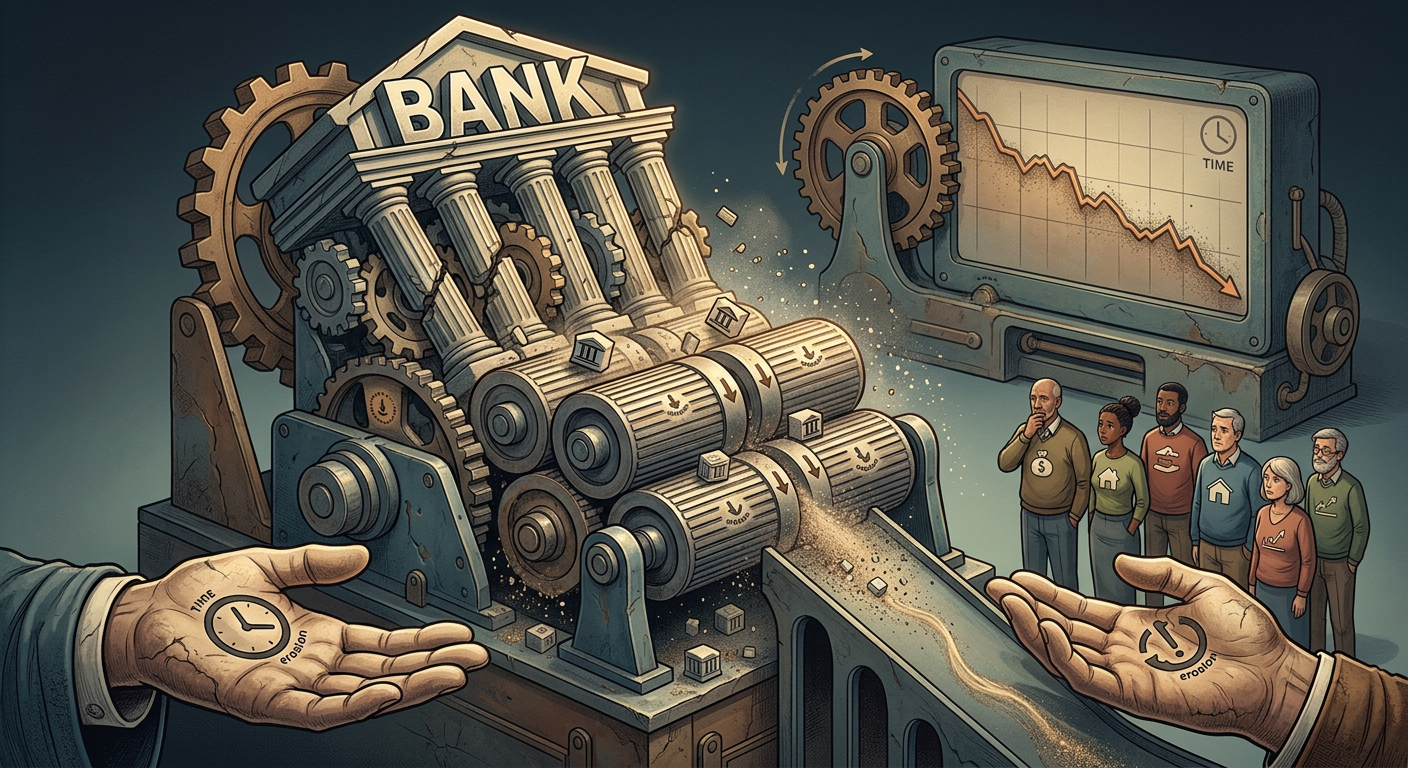
The real game is underneath: funding costs, deposit behavior, and the slow-motion pressure on regional banks and commercial real estate. When the Street says "soft landing," it really means "margin compression."
Quick backdrop, because it matters for everything below: June CPI (out yesterday) cooled to roughly 3.9% on the headline as June gas prices fell — but core inflation stayed sticky near 3%, and with the Iran shipping blockade back on and oil rebounding toward $80, that "cooling" is already partly stale. Higher-for-longer is still the regime. That's good for bank margins and bad for over-levered borrowers — which is the whole story today.
1) Big Bank Earnings Are Theater — The Signal Is Deposits + Funding Costs
Every earnings season starts the same way: the megabanks report, headlines scream "beats," and the talking heads declare the economy healthy. (Right on cue, JPMorgan and Wells Fargo both beat yesterday.) Here's what actually matters underneath the EPS line: deposit competition (when deposits get expensive, the whole system becomes a lower-return business), funding mix (leaning harder on wholesale funding tells you deposits aren't as "sticky" as the PowerPoint claims), and balance-sheet velocity (loan growth funded by expensive liabilities isn't bullish — it's a future problem).
And here's the uncomfortable part: the big banks can muscle through this. Regionals can't. The market will keep rewarding strength in the top-tier franchises with genuine deposit moats — so that's where you should anchor, while treating the second and third tier with far more care (Section 3).
Company: Wells Fargo (SYM: WFC)
A top-tier franchise with a massive low-cost deposit base — and a fresh growth catalyst now that its asset cap is gone
Wells Fargo is the rare top-tier bank that's also a catch-up story. It sits on roughly $2.2 trillion in assets and one of the country's largest, stickiest consumer deposit franchises — exactly the low-cost funding advantage this section is about. The catalyst: the Federal Reserve's seven-year asset cap (imposed after the fake-accounts scandal) was finally lifted in June 2025, and this was the first full year Wells could actually grow its balance sheet again. Yesterday's Q2 print beat (EPS ~$1.96 vs. ~$1.73 expected, revenue ~$22.6 billion), and here's the kicker for value hunters: WFC has lagged its peers badly over the past year (up ~5% while Bank of America rose ~26% and Citi ~60%), so you're buying a top-tier franchise that hasn't run.
WFC trades around $86–88, below the ~$96 average analyst target. The honest caveats: it's still a bank, so a sharp economic downturn hits credit costs and loan demand; its post-cap growth story has to actually show up in net interest income, or the thesis weakens; consumer-credit trends bear watching; and its regulatory-scrutiny history means execution has to stay clean. This is "own the top-tier franchise while it's still the cheap one," not a risk-free coupon.
Bottom line: Ignore the "beat." Watch deposits, funding costs, and liquidity language. That's where the next banking winners and losers get sorted — and the top-tier deposit franchises are where you want to be.
2) CPI Is a Headline Trade — Credit Is a Slow Trade (And It's Tight)
CPI days are designed to hypnotize you: one number hits, futures spike, and everyone pretends 30 seconds of price action revealed the next six months. Here's what I care about more: are lenders actually loosening, or just pretending? Are small companies refinancing at tolerable terms? Is consumer credit rolling over quietly even as the index levitates?
Inflation can cool and credit can stay restrictive — and for small/mid-cap stocks, credit is oxygen. So there's no single ticker here; just a discipline. When you screen underfollowed names this season, sort them into two buckets: businesses that can self-fund (positive free cash flow, cash on hand, no near-term maturity wall) versus serial refinancers that need the capital markets to reopen on friendly terms every 12–18 months. Treat the second bucket like a landmine, no matter how good the story sounds. In a higher-for-longer world with sticky core inflation, the self-funders quietly buy assets cheap while the refinancers dilute you to survive.
Bottom line: CPI is the spark. Credit is the fuel. In this market, the fuel is still scarce — so own the businesses that don't need it.
3) Regional Banks: The Next "Crisis" Won't Be a Crash — It'll Be an Earnings Grinder
The public thinks banking risk looks like a weekend bailout. Most of the time it doesn't. It looks like net interest margin drifting lower every quarter, provisions creeping up, regulators "encouraging" conservatism, and expensive deposits that never get cheap again. Now layer on commercial real estate: even if you don't believe in a doom loop, the math is ugly — refinancing risk + higher cap rates + lower transaction volume = bad optics and worse earnings.
So the trade isn't "buy the dip" in every regional. It's to separate the banks with real deposit franchises and conservatively-underwritten CRE books from the ones whose model only worked when money was free. Your diagnostic checklist: How low and sticky are deposit costs (a low "deposit beta")? How concentrated is the CRE book — especially office? What's the reserve coverage against those loans? And is the bank funding itself with core deposits or leaning on pricey wholesale money? Here's a concrete example of the survivor profile.
Company: M&T Bank (SYM: MTB)
A disciplined super-regional with a strong core-deposit franchise and a long track record of surviving credit cycles
M&T is the archetype of a survivor regional. It runs a deep, low-cost deposit franchise (guiding to ~$165 billion in deposits), has a reputation for disciplined underwriting through multiple cycles, posts superior margins and asset quality versus many peers, carries healthy capital, and is returning cash through a $5 billion buyback. If you're going to own a regional in a grind market, this is the profile you want — real deposits, conservative culture, capital to spare.
Now the caveats, and they're important: M&T is a meaningful CRE lender, and while management is actively moderating that exposure (pivoting toward commercial-and-industrial and consumer lending), its commercial real estate book — especially office — is the single thing to watch every quarter. Just as important: the stock is near its all-time high (~$240), it's trading right at the average analyst target (limited upside from here), Baird recently downgraded it to Neutral, and it reports this very morning — so rather than chase it at the open, use today's release as a live stress-test of this whole section: listen to what management says about deposit costs, CRE reserves, and office. If the survivor thesis is intact, wait for a better entry.
Bottom line: Regional-bank pain can last years without a single dramatic headline. Own the survivors — real deposits, conservative CRE — and avoid the "money-was-free" models entirely. Grind markets shake out the unprepared.
4) The Underfollowed Defense Angle: The "Second-Order Suppliers" Get Paid First
Defense headlines are noisy; the better trade is structural. When governments move from talking to buying, the prime contractors win eventually — but the near-term cash flow often shows up first in the supply chain: components, electronic subsystems, propulsion and materials, maintenance and readiness. These are smaller businesses that get re-rated fast when backlogs firm up, and Wall Street ignores them because they're not household tickers. Look for repeatable revenue (spares, sustainment, services), exposure to munitions + air defense + drones rather than just big platforms, and management teams that don't destroy shareholders chasing "growth."
Company: Mercury Systems (SYM: MRCY)
Domestic maker of secure processing and electronic subsystems for radar, electronic warfare, and missile defense — a "second-order" supplier in the sweet spot of the budget
Mercury is almost a checklist match for this section. It makes the ruggedized, secure signal- and data-processing subsystems that go inside radars, electronic-warfare systems, missiles, and missile-defense platforms — exactly the "electronic subsystems + air defense" niche the draft flags — and its ITAR-compliant, "Made in America" microelectronics give it a moat as the Pentagon pushes domestic sourcing. After a rough 2022–2024 (activist pressure, margin problems), the turnaround under new management is bearing fruit: a record ~$1.6 billion backlog (up ~18% year-over-year), improving margins, and rising free cash flow, with a $200 million buyback in place. As a cleaned-up pure-play, it's also a perennial M&A target for larger primes or private equity.
The caveats are significant and I won't soft-pedal them: the stock has surged ~120% in the past year, it now trades above the median analyst target (~$105 vs. ~$123), Goldman Sachs actually rates it a Sell ($68 target), and the turnaround is still converting low-margin legacy backlog into consistent GAAP profitability — so any revenue "air pocket" would sting a richly-priced stock. This is a fantastic thematic fit that has already run hard; treat it as a watchlist/pullback name, not a chase. (For a less-extended, lower-octane way to play "readiness and sustainment," Leidos and Moog are worth your own diligence.)
Bottom line: Defense is a multi-year theme, but the best entries show up in the boring suppliers — and the best of those, like Mercury, have already been discovered, so patience on price is part of the trade.
Before You Go
The Street's trick is always the same: keep you watching the headline. Our job is to keep you watching the plumbing — deposits, funding costs, credit terms, and the quiet grind in regionals and CRE. Because plumbing is where markets break, and where retail investors can still find edge.
Found this helpful? Share it with others.
Written by Behind the Markets