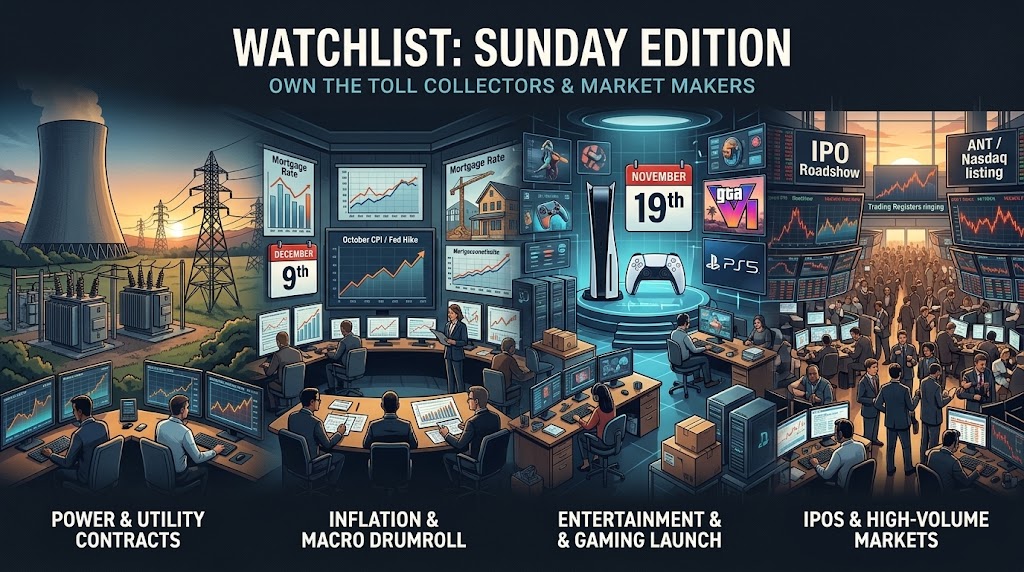
Morning Watchlist: Sunday Edition
The Week in Review A quick note from Behind the Markets
It's Sunday morning — the quiet shelf between a wild week and a loaded one. One honesty note: we go to press Friday morning, before the October jobs number hit the tape and before Friday's closing bell — so you know two things we didn't. Keep both in your pocket as you read.
Here's the docket. The power companies report Monday morning and Take-Two reports Monday night, eleven days before the biggest entertainment launch in history. Tuesday at 8:30, the October CPI — the last inflation report the Fed sees before its December 9 decision. Wednesday is Veterans Day: stocks trade, the bond market rests. Thursday night, Cisco and Applied Materials grade the tech aisle. Friday, producer prices. And somewhere in there, if Bloomberg has it right, the biggest IPO roadshow ever attempted gets rolling.
Four stories this morning. Four pairings.
Let's get into it.
1) Monday Morning, the Power Bill Arrives
The AI trade just lived through its worst stretch since June, and the argument now runs on one question: is the demand real, or is it a story the GPU stocks told each other?
Monday before the open, two companies answer with invoices instead of narratives. Constellation Energy — the largest nuclear fleet in America — reports with the Street expecting $3.90 a share; NRG Energy reports the same morning. These are the companies that sell electrons to the data centers everyone spent Thursday panicking about. You can argue with a growth multiple. It's harder to argue with a signed power contract. Constellation closed Thursday near $239, well off its highs this year, so the bar is not set for applause.
But the utilities are landlords. When a landlord tells you every building is full and tenants are lined up down the block, you look for the construction crew.
The pairing: Argan (AGX) — Watch
Argan is one of the few companies in America that builds large gas-fired power plants, start to finish. Its backlog stood at about $2.5 billion as of July 31 — including four U.S. gas plants totaling more than 4.1 gigawatts — and it carried roughly $900 million in cash and no debt at its last fiscal year-end. Wall Street expects earnings up about 41% this fiscal year.
So why Watch and not Buy? Because the backlog came DOWN from $2.9 billion — no major new power award this fiscal year — a pair of industrial projects dinged margins, and the stock, up about 25% this year, costs near 25 times next year's expected earnings. A builder's stock runs on the next contract. The entrance is exactly that: the next major award, and Monday's utility calls are where you'll hear it coming — utilities don't order power plants quietly. The kill: a data-center capex freeze that leaves the awards drawer shut.
2) Tuesday, 8:30, the Last Word Before December
Here's the week's main event. The October CPI lands Tuesday morning, and it is the final consumer inflation reading the Fed sees before December 9 — the November report arrives December 10, one day too late. With a December hike priced above 80% for weeks, Tuesday is effectively the hike's confirmation hearing. Forecasters we read, including Continuum Economics, pencil in a milder month: about 0.2% on both headline and core, after two straight 0.3% core prints.
When the crowd is this sure, a hot print confirms what's already paid for. A cold print is the surprise — the payout sits on the side of the coin the crowd stopped watching.
The pairing: M/I Homes (MHO) — Watch
Longtime readers know this name, and the scar. We bought the builder on August 20th at about $154.60, betting on falling mortgage rates. Then Chair Warsh turned hawkish, yields spiked, and on September 3rd we flipped to Sell near $146 and took the 5.5% loss rather than fight the Fed.
The stock now sits near $138, around 9 times trailing earnings, with the average analyst target up at $164. And the smartest capital in America already shopped this aisle: Berkshire Hathaway agreed in June to buy builder Taylor Morrison outright, in cash, at a 24% premium. Buying a homebuilder with mortgages near 7% is buying the snow shovel in a heat wave; the whole question is whether the weather ever turns. The entrance: Tuesday's core print coming in cold and December's hike odds cracking — the first weather report that matters. If it runs hot, the hike is locked, and we stay on the bench while the stock likely gets cheaper. We're not buying a coin flip. We're naming which side we'd buy after the coin lands.
3) The Last Report Card Before the Biggest Launch Ever
Monday after the close, Take-Two Interactive reports — its final earnings before Grand Theft Auto VI arrives November 19. Pre-loading starts Wednesday the 12th. Analyst trackers put pre-order sales north of $600 million with two weeks still to go, and Morningstar projects 60 to 70 million copies sold in fiscal 2027. Bank of America rates it Buy with a $368 target against Thursday's roughly $213 close.
So why isn't Take-Two the pairing? Because the loudest seat is priced for perfection and has exactly one job between now and the 19th: don't slip. The $79.99 sticker already disappointed investors who had dreamed of $100, and the stock sold that news. We'd rather own the stadium than the headliner.
The pairing: Sony (SONY) — Buy
Every copy of GTA VI sold on a PlayStation pays Sony the platform's customary cut of roughly 30% — and there are 97.9 million PS5s already in living rooms. On Thursday, Sony reported game-division operating profit up 83%, raised its full-year operating income forecast 15% to roughly $11.8 billion, and said 78% of full-game sales are now digital — the high-margin kind. The stock jumped 7% in Tokyo on the news; the U.S. shares went into the report around $25, about 21 times earnings. The market multiple, for the tollbooth on the biggest entertainment launch ever — plus a PlayStation 6 that management says is "progressing as scheduled."
The honest warts: Sony has reportedly told partners that PS5 supply will be tight into next year, squeezed by memory prices and tariffs — the same memory squeeze that pays our Micron position pinches console makers. But GTA VI doesn't need new consoles. The toll road is already built; November 19th just opens the on-ramp. The kill: a launch delay into next year, or a yen spike that eats the translation.
4) The Biggest Roadshow on Earth (Maybe This Week)
Anthropic filed to list on Nasdaq under "ANT" on October 26, and the November 2 amendment added a quarter with revenue near $17 billion. The talk around the deal: a valuation between $1.5 and $2 trillion, raising $100 billion or more — the largest flotation ever attempted. Bloomberg reports the roadshow could begin as early as this week, with a debut targeted before Thanksgiving. The tell: a price-range amendment on EDGAR. That's the starting gun.
We've had seats at this parade since October — Goldman Sachs, flagged October 2nd, and Nasdaq itself, a Watch from October 29th. But there's a third toll nobody prices: once the stock trades, somebody has to make the market — in the shares, in the index flows, in everything that reprices around a trillion-dollar newcomer.
The pairing: Virtu Financial (VIRT) — Buy (again)
We flagged Virtu on September 21st at $57.26. It sits near $54 — about 6% against us — which is why we're repeating ourselves: on Thursday the company showed receipts. Revenue up 40% to $1.15 billion, trading income up 55%, adjusted earnings of $1.77 a share against $1.05 a year ago. The stock costs roughly 7.5 times next year's expected earnings. The S&P 500: 21.
A market maker is the stallholder at a farmers market who buys at 99 cents and sells at a dollar one, all day long. He doesn't care whether tomatoes are up or down — only that the market is crowded. Now read this week's calendar again: a CPI coin flip Tuesday, a half-staffed bond market Wednesday, the chip aisle's exams Thursday, and the biggest IPO in history warming up its megaphone. We're not betting on the direction of anything. We're buying the register that rings either way. The kill, unchanged from September: a long volatility drought. Look at the tape lately and tell us where the drought is.
Before You Go
That's the watchlist. A power bill Monday, a coin flip Tuesday, a report card before the launch, and a roadshow for the record books — one theme throughout: own the toll collectors, and name your side of the coin flips in advance.
The week's biggest moment comes Tuesday at 8:30 AM: the October CPI, the Fed's last look at consumer prices before December 9. Read the core line before the headline — that's the one the hike case stands on, and the one our M/I Homes entrance hangs on. Then Thursday after the close, Applied Materials grades the entire chip-equipment aisle, our Lam Research and FormFactor positions included. And remember the two things you know that we didn't Friday morning: the jobs number and Friday's close. Grade Tuesday's setup with both in hand.
Have a wonderful Sunday.
Found this helpful? Share it with others.
Written by Behind The Markets