Morning Watchlist: Saturday Edition
The Week in Review A quick note from Behind the Markets
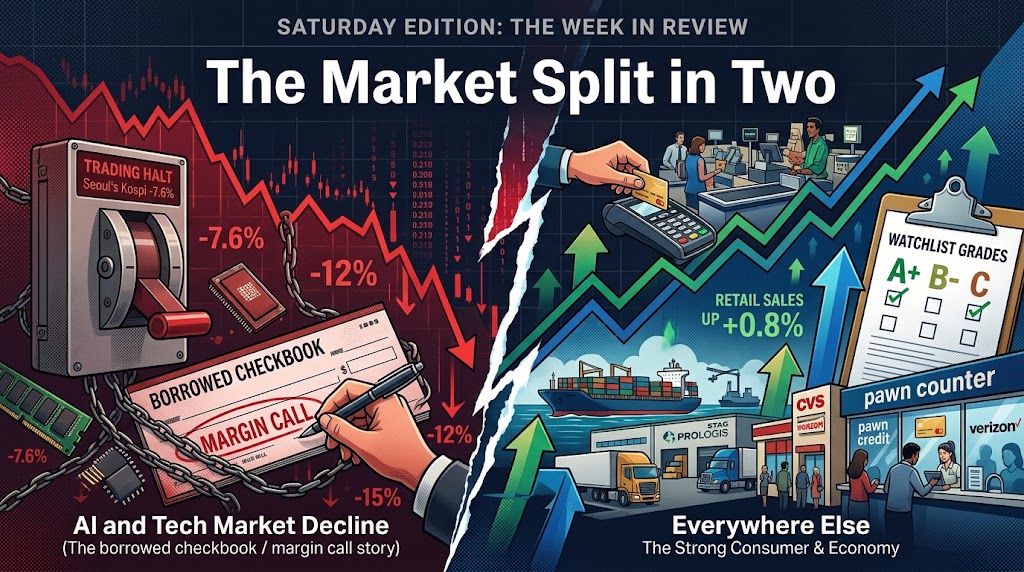
It's Saturday morning, and this was the week the market split in two.
On Thursday, roughly seven of every ten stocks in the S&P 500 rose — and the index finished about flat. The Dow climbed more than 400 points the same morning Seoul's Kospi fell 7.6% through a circuit breaker. And the 10-year Treasury, which had topped 5.30% earlier in the week, rallied all the way down to 5.07% on a day wholesale inflation printed a 1.3% monthly jump.
Money didn't leave the market this week. It left one checkbook — the borrowed one funding the AI build-out — and hid everywhere else.
Saturday is when we grade our own card against that split: all eighteen calls from this week's editions, plus the open names the week graded for us. One press note, as always: we go to press Thursday midday, so Friday's session belongs to you, not to us — it's on your Monday checklist below. Four stops on the tour.
Let's get into it.
1) The Margin Call Found the Borrowed Checkbook
The week's loudest story ran Monday through Thursday without a breath: China's CXMT memory claim torched Seoul on Monday and Tuesday, ASML said Wednesday it's sold out through 2028, TSMC posted a sixth straight record on Thursday — and the Kospi fell 7.6% through a trading halt anyway, because the argument was never about demand. It was about who's paying for the build-out, and with what.
CoreWeave, Friday's Sell for holders at $65.78, kept falling on day one — $64.32 by Thursday midday — as its measured credit risk hit an all-time high, Bernstein initiated it at Sell citing "fragile economics," and Mizuho cut its target from $115 to $88. Nvidia's Jensen Huang offered the faint-praise defense that Nvidia "does not need to backstop" the company. The AP put a number on the treadmill: about $4.4 billion of debt payments due in the second half of 2026, and $6.2 billion more in 2027. When the lenders charge 15%, the stockholders stand at the back of that line. Sell stands (for holders).
Micron finally felt it. Thursday the stock swung from $858 to $922 and sat near $915 at our press time — the first prints below our $925 September flag — on China worries and talk of 2029 oversupply. Read the kill switch again: DRAM contract prices actually cracking. A financing panic isn't that, and $150 billion of revenue sits under defined-price contracts. Still Buy.
The quiet winner of the memory war was Wednesday's bakery: HP, flagged Watch at $29.87, closed Wednesday at $30.46, up 2% while every mill on Earth burned. Still Watch. And the watch column did its best work in the chip aisle: Entegris, Sunday's Watch at $162.19, traded at $143.17 Thursday morning — down about 12%, 6.5% of it Thursday alone, straight through fresh Buy initiations from Barclays and Truist. The mid-$130s entrance we named is now about 6% away. Watching cost nothing; buying Sunday's close would have cost 12%. Still Watch — check Monday. Photronics drifted 3.8% lower to $28.01, toward its own $25 line, and Lam Research's entrance (the October 28th print, or ~$300) is unchanged. Still Watch, both.
2) The Banks Confessed. The Shopper Kept Swiping.
Tuesday was exam day, and our October 2nd Goldman Sachs Buy passed loudly — $17.01 a share against roughly $13 expected, equities up 72% — which we graded midweek. Here's the honest Saturday footnote: the market didn't care. Goldman traded at $862.48 Thursday, about 6% below our $916 flag, as RBC cut its target from $1,220 to $1,010 and MarketWatch summarized the new worry in one line: big banks see risks in financing the AI boom — and keep writing the checks. The dealer got paid at every table; the crowd is now auditing the casino's credit line. The thesis was the cycle, not the week. Still Buy.
Meanwhile the consumer the banks vouched for showed receipts. Thursday morning: September retail sales up 0.8% against the 0.4% expected, jobless claims at 199,000 — alongside a producer-price report running 6.3% hotter year over year. Translation: the shopper is still swiping, and still paying up (gas-station sales alone rose 6.4% in a month).
That's the road our consumer-credit shelf is built on. Synchrony, Wednesday's Buy at $73.62, traded at $71.88 midweek — down about 2.4% as the target-cutters kept working into Tuesday's report, which was always the exam. Still Buy. Encore Capital, Sunday's junkyard Buy at $100.06, printed a fresh 52-week high of $105.74 on Tuesday — up nearly 6% in two days — then handed most of it back in Wednesday's tape to close at $100.86, still just above the flag, with Northland raising its target to $124. Still Buy. And FirstCash, Friday's pawn-counter Watch at $216.53, sat at $217.28 Thursday as Canaccord raised its target to $265 — the crowd still arriving at the counter, which is why we wait for the October 22nd print or the $190s. Still Watch.
3) The Cleanup Invoices Went Out
Bank of America's $1.2 billion fine was Tuesday's headline; the billing cycle it starts was our Thursday story — and the two names we paired with it split the week between them.
FTI Consulting, Thursday's Buy at $137.89, closed Wednesday at $140.09, up 1.6% — and on Tuesday named new leadership for Compass Lexecon, the economics arm whose departures created the discount in the first place. The repair we were waiting on is being made while the consent-order work piles up. Reports October 29th. Still Buy. NICE took the week's worst Buy grade: $111 by Wednesday's close, down 5.4% from Monday's flag, on no company news we could find. The AI-disruption fear that makes it cheap simply got louder in a week when everything labeled "AI" got repriced. The receipts haven't moved — two nine-figure AML fines in eight days, Actimize still in reported $2 billion sale talks. Still Buy.
Healthcare's cleanup story graded better. CVS, Wednesday's Buy at $87.74, traded at $91.68 Thursday midday — up 4.5% — and even wrote its own, much smaller cleanup check along the way: a $315 million opioid settlement with the Justice Department that the market shrugged off in an afternoon. UnitedHealth's Tuesday beat validated the repair playbook Aetna is running. Still Buy. And Tenet, Sunday's hospital Buy at $260.57, closed Wednesday at $271.60 — up 4.2%, crossing its 200-day average, with Argus raising its target to $284 — before softening with Thursday's tape. The landlord never did complain about the heating bill. Reports October 29th. Still Buy.
4) Landlords, Tollbooths, and the Refinery Gate
The bond rally that ended the week re-marked everything on this page that collects rent or yield — mostly in our favor.
Verizon traded at $45.09 Thursday midday, about 5% above Monday's ~$43 flag, helped Thursday by headlines on the first outdoor 6G field call with Ericsson; Bernstein trimmed its target to $45 on the Starlink risk we named at the flag. The toll road is recovering its markdown. Still Buy. Crown Castle round-tripped to $79.38 Wednesday — no fade toward the low $70s, no signed SpaceX lease either — so Wednesday's October 21st report remains the entrance. Still Watch. RenaissanceRe closed Wednesday at $339.51, up 2.5% from Tuesday's flag, with the crowd arguing out loud: BofA's target sits at $428, Wells Fargo's at $319. The storm fund reports October 27th. Still Buy. STAG, Friday's warehouse Buy at the $36.36 flag, closed Wednesday at $35.88 — a newborn marked down 1.3% with the REIT tape before Thursday's yield relief. The 38% raise is in the contracts either way. Still Buy.
Albertsons rose 2.2% to $13.08 while the crowd split loudly over it — Goldman and JPMorgan downgraded to Neutral, RBC raised its target to $16, and the Journal reported Albertsons is seeking $8 billion from Kroger over their failed merger. A courtroom claim is a lottery ticket, not a turnaround plan; we're still waiting for the menu. Still Watch.
And the refinery gate, honestly kept. Valero sat at $445.86 Thursday midday, roughly at the flag, while the targets chased from both directions — Wells Fargo to $485, Citi from $302 to $485. The entrance stays the October 22nd print. Still Watch. PBF is the week's humility paragraph: we said sell at $84.27 on Tuesday, and it closed Wednesday at $89.51 — 6% above the flag — before easing to $86.37 Thursday, with Citi, Mizuho, and Goldman all raising targets as record cracks outran the policy campaign. Selling into strength means sometimes watching the strength continue. The four-program campaign against the spread hasn't billed yet; the October 29th report is the referee. Sell stands (for holders).
Before You Go
The scoreboard. Eighteen calls this week — nine Buys, seven Watches, two Sells. Through Thursday midday, six of the nine Buys were green: Verizon +4.9%, CVS +4.5%, Tenet +4.2%, RenaissanceRe +2.5%, FTI +1.6%, Encore +0.8%. Tuition ran at NICE (-5.4%), Synchrony (-2.4%), and STAG (-1.3%). The watch column paid for the whole page again: Entegris fell 12% while we stood outside, Photronics drifted toward its line, and FirstCash, Crown Castle, Valero, Albertsons, and HP all sat within a couple points of their flags — seven entrances named, none chased. The sells split: CoreWeave fell on day one; PBF rose against us, and we said so. Same system as every week: buy the story at the fair price, name what kills it, and let the exciting version go to somebody else.
Your Monday checklist, in order. First, Friday's close: did the market's split hold — the 10-year near 5.07%, the Dow green while the AI tape bled — and did Entegris keep sliding toward the mid-$130s entrance while Micron defended the $925 line? Second, Tuesday the 20th: Synchrony's exam, plus Ally, Western Alliance, and Nasdaq. Third, Wednesday the 21st is a tripleheader for this page — Crown Castle's entrance exam, Knight-Swift's, and First American's earnings. Fourth, Thursday the 22nd: Valero's entrance print, FirstCash's, and Alaska Air's long-watched fuel bill. Fifth, Sunday the 25th: Brazil's runoff — StoneCo's entrance, win or washout — with a live Fed meeting two days behind it and hike odds at a coin flip.
Found this helpful? Share it with others.
Written by Behind The Markets